financial wellness
Home buyers with lower credit scores pay an extra $104,000 in mortgage costs

Last Updated on May 16, 2024 by Daily News Staff
- Improving your credit score can save hundreds a month on your mortgage
- A borrower with a “fair” credit score could pay $103,626 more over the life of a 30-year mortgage for the same home than an otherwise identical borrower with an “excellent” score would
- Barriers to housing that result from credit issues are often more profound for people of color
SEATTLE, July 28, 2022 /PRNewswire/ — Elevated home prices and rising interest rates are feeding into housing affordability woes for potential buyers, especially those with lower credit scores. A new Zillow analysis shows that, nationally, buyers with “fair” credit could be paying up to $288 more on their monthly mortgage payment than those with “excellent” credit.
Today’s home shoppers can expect to pay around 62% more per month to buy a typically priced U.S. home than they would have a year ago. Zillow examined credit scores against current mortgage rates and found that such monthly cost increases are exacerbated for millions of Americans with low credit scores or less than perfect credit histories.
A borrower with an “excellent” credit score — between 760 and 850 — can qualify for a 30-year fixed-rate mortgage with a 5.099% interest rate1. For the same loan, a similar borrower with a “fair” credit score — between 620 and 639 — qualifies for a 6.688% rate1. This equates to a $288 difference in monthly mortgage payments and nearly $103,626 in interest over the life of a 30-year fixed loan, based on the current price of a typical U.S. home ($354,165)2.
“When you are thinking about buying a home, the best first step you can take is to fully understand your financial picture, what you can afford and your outstanding debts or obligations,” said Libby Cooper, Zillow Home Loans vice president. “If you find you have low credit, take realistic steps to improve your credit score by doing things like disputing possible report errors and paying down as much debt as possible. This could increase the amount of home loan you qualify for.”
The chart below illustrates how a buyer’s credit profile plays an important role in how much a home ultimately costs. Buyers who make raising their credit score part of their initial steps in the home-buying process typically have more buying power and lower monthly payments.
The cost of buying a typically priced U.S. home based on credit scores3FICO® Score Estimated Annual
Percentage Rate1Monthly Payment Total Loan Cost 760–850 5.099 % $1,538 $553,743 700–759 5.321 % $1,557 $567,739 680–699 5.498 % $1,608 $579,014 660–679 5.712 % $1,647 $592,782 640–659 6.142 % $1,725 $620,882 620–639 6.688 % $1,826 $657,369
There is a direct correlation between credit security — having a strong credit history and structural access to credit offerings — and higher homeownership rates. The homeownership rate is lower in counties that are more “credit insecure,” meaning they are home to high numbers of residents with poor or no credit history. That cuts off millions — particularly Black and Latinx residents — from the wealth-building advantages of homeownership. Additionally, Black applicants are denied a mortgage at a rate 84% higher than white applicants, and credit history is the most common reason cited for those denials. Limited traditional financial services in Black and other communities of color are a significant factor in the lack of credit history and the inability to build a high credit score.
Fannie Mae and Freddie Mac recently adopted policies that include timely rent payments in their automated underwriting systems. Lenders and brokers can submit bank account data (with borrower permission) to identify 12 months of prompt rent payments to help potential borrowers qualify for a mortgage.
“While inclusion of timely rent payments doesn’t change a borrower’s credit score, it can have a positive impact on how lenders view a borrower’s credit worthiness. This move shows how effective policy changes can help consumers build a strong financial foundation that unlocks homeownership,” said Cooper.
About Zillow Group:
Zillow Group, Inc. (NASDAQ: Z and ZG) is reimagining real estate to make it easier to unlock life’s next chapter. As the most visited real estate website in the United States, Zillow® and its affiliates offer customers an on-demand experience for selling, buying, renting or financing with transparency and ease.
Zillow Group’s affiliates and subsidiaries include Zillow®, Zillow Offers®, Zillow Premier Agent®, Zillow Home Loans™, Zillow Closing Services™, Zillow Homes, Inc., Trulia®, Out East®, ShowingTime®, Bridge Interactive®, dotloop®, StreetEasy® and HotPads®. Zillow Home Loans, LLC is an Equal Housing Lender, NMLS #10287 (www.nmlsconsumeraccess.org).
1 Based on the FICO Loan Savings Calculator on myfico.com. Rates current as of July 26, 2022.
2 According to the Zillow Home Value Index.
3 Loan calculations assume a 20% down payment on a home cost of $354,165 with a 30-year fixed mortgage. Total loan cost includes the loan value and interest cost over the life of the loan.
SOURCE Zillow


child education
Preparing the Next Generation for Economic Mobility in an AI-Driven World
AI-Driven World: Within only a few years, AI has already changed many things about the world and workforce. Entry-level jobs, particularly the ones relying on routine and predictable tasks, are increasingly disappearing to automation, leaving young people wondering how to launch their careers and futures. To learn what preparing students for the future may look like in practice, consider these tips.
Preparing the Next Generation for Economic Mobility in an AI-Driven World
(Feature Impact) Within only a few years, AI has already changed many things about the world and workforce. Entry-level jobs, particularly the ones relying on routine and predictable tasks, are increasingly disappearing to automation, leaving young people wondering how to launch their careers and futures.
Access to economic mobility – the ability to change your income or wealth – doesn’t just rely on technical knowledge and skills but on leaning into humanity. Being able to think outside the box, collaborate, solve problems and grow as a person can open doors in life and at work. AI may be changing the world, but in change lies opportunity. The students who can adapt quickly are more likely to prosper as the economy continues to reshape itself.
To learn what preparing students for the future may look like in practice, consider these tips from the economic and career experts at Junior Achievement.
Build the Kinds of Skills AI Can’t Replace
Young people facing AI as their competition can get a boost from cultivating the uniquely human skills technology can’t replicate. Educators, parents and other adults in kids’ lives can help them develop increasingly important soft skills like critical thinking, communication, teamwork and leadership, which can translate to many different careers. Hands-on skills can fit into this category as well, like the kinds required in entrepreneurship and the trades.
Provide Real-World Experiences
When young people have the chance to test themselves in a real-world setting, it lets them hone their interests, skills and confidence before the time comes to make major decisions about their futures. As early as elementary school, experiential learning activities like Junior Achievement’s Biztown allow students to operate businesses, work with others, manage finances and solve problems, combining in-class learning with hands-on simulations. As kids grow up, other options can include job shadowing, internships and entrepreneurship experiments – all ways to build durable social and professional skills that can help them succeed.
Teach Foundational Financial Literacy
Earning money is only part of the equation for a healthy financial future; equally important is understanding how to manage it. As kids prepare to earn their first sources of income, make sure they’re also equipped with practical financial skills like budgeting, saving, investing, using credit wisely and planning for future goals. Giving them these tools early helps them make informed decisions about their long-term economic advancement.
Connect Students with Employers and Opportunities
Sometimes, all a student needs to succeed is someone who’s willing to give them a chance. Young people in a position to meet business professionals in (and beyond) their communities may be able to turn those connections into future opportunities. This can happen naturally as they seek real-world experiences through apprenticeships, mentorship programs, career fairs and more.
Programs like Junior Achievement’s 3DE puts students in authentic business challenges, connecting them with educators, business partners and volunteers as they work in teams to complete case experiences. This not only gives young people the opportunity to meet potential employers or mentors, it also lets them demonstrate critical thinking, social skills and real-world competence.
Visit jausa.ja.org for more ideas to help young people gain the confidence and connections needed to achieve economic mobility in a changing world.
Photo courtesy of Shutterstock
SOURCE:
Consumer Corner
5 Hidden Ways to Save on Home Insurance Costs
Lowering Home Insurance Costs? Many home improvements offer an added bonus of unlocking insurance discounts, but these savings opportunities can easily fly under the radar when you aren’t actively on the lookout for them.
5 Hidden Ways to Save on Home Insurance Costs
(Feature Impact) When you’re planning home improvements, you’re often thinking about improving the comfort, safety, aesthetic or value of your home. Many changes and renovations have the added bonus of unlocking insurance discounts, but these savings opportunities can easily fly under the radar when you aren’t actively on the lookout for them.
“Homeowners tend to think about their insurance when they buy the house or when they have a claim, but a lot can change in between,” said Larry Anderson, director of underwriting operations at Mercury Insurance. “Something as simple as reviewing your policy with your agent once a year can help make sure your coverage still reflects your home today and identify improvements or other factors that may qualify you for additional savings.”
The experts at Mercury Insurance, a multiple-line insurance carrier emphasizing competitive rates and excellent customer service, encourage homeowners to consider these five ways to save on home insurance costs.
Updating Older Parts of the Home
As a home ages, it’s wise to look at what parts and systems may be deteriorating and need upgrades for modernity or safety reasons. Replacing older electrical, plumbing or other major systems can protect your home from emergencies and loss risks. Depending on the state you live in, your specific policy and the improvements you made, it can also qualify your property for an updated-home insurance discount.
Keep records of major improvements – including receipts, work permits and information about when the work was completed – and plan to discuss the upgrades during your next insurance review.
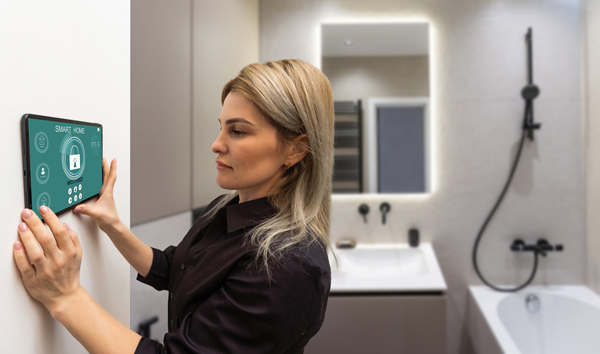 Adding Protective Technology
Beyond replacing the batteries in your smoke detectors, you can outfit your home with a variety of protective devices that make a difference to insurers. Consider options like monitored burglar and fire alarms, smart water sensors and automatic water shutoff systems designed to detect problems before they become major losses. Remember, while security upgrades can make your home less risky to insure, they won’t save you money if your insurer doesn’t know you’ve installed them.
Improving Resilience to Damage
If you live in an area prone to extreme weather or other hazards, resilience upgrades could both safeguard your home and access insurance savings. Depending on your location, qualifying improvements could include a stronger roof, wildfire mitigation measures or flood defense options. Local insurance agents can provide more specific guidance on ways to make your home less vulnerable to damage – or whether you’re eligible for discounts because of work you’ve already completed.
Qualifying for Community Programs
Even if you haven’t personally made renovations to your home, certain changes in your community could help you save on insurance. That could include local wildfire mitigation measures, membership in a qualifying homeowners association or other neighborhood characteristics that affect coverage options, but specific programs vary by location.
Reviewing Insurance Products and Discounts
Whether something significant has changed in your home or community or not, it’s always valuable to review your insurance coverage on a regular basis. For instance, there may be new products or discounts that simply didn’t exist when you originally purchased your policy. Beyond savings considerations alone, ask your agent questions to make sure your coverage still reflects your circumstances and goals.
“Finding savings is always welcome, but the bigger goal of a policy review is making sure your insurance keeps pace with your life and your home,” Anderson said. “A house isn’t static. We improve it, maintain it and protect it in new ways over time. Your insurance should keep up with those changes.”
For more information on homeowner coverage and discount eligibility, visit MercuryInsurance.com.
Questions to Consider During Your Annual Insurance Checkup
An annual insurance review is an opportunity to look for savings and update coverage. Use these questions as a jumping-off point for discussions with your agent:
- What has changed about my home?
- What has changed about my property or community?
- Have my circumstances changed?
- Are discounts available today that weren’t when I purchased my policy?
- Does my coverage still reflect what it would cost to repair or rebuild my home today?
Photos courtesy of Shuttersotck

SOURCE:
📰 Enjoying STM Daily News? Join the conversation!
💬 Leave a comment, share your thoughts, and subscribe to our newsletter for the latest stories, updates, and “News You Can Use This Moment!” delivered to your inbox.
Stay connected with STM Daily News!
Health and Life Insurance
Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think
Life is the most valuable thing you have – and like all valuable things, it should be insured. Even thinking about life insurance can be stressful, so it’s one of those things that’s easy to put off and tell yourself you’ll do another day. Consider these four ways to make getting life insurance simpler than you thought.
Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think
(Feature Impact) Life is the most valuable thing you have – and like all valuable things, it should be insured. Even thinking about life insurance can be stressful, so it’s one of those things that’s easy to put off and tell yourself you’ll do another day.
If that’s how you feel, you aren’t alone. According to the 2026 Life Happens Life Insurance Survey, nearly half (46%) of U.S. adults have getting life insurance on their to-do list but plan to deal with it later or not at all. Confusion, procrastination and cost concerns are among the main reasons people kick this can down the road, according to 45% of respondents.
Yet the survey also uncovered an interesting disconnect: 69% of Americans said they personally know someone who had life insurance or whose family used a life insurance policy, most often a parent or parent figure (33%), but still haven’t made getting coverage a priority.
“Life insurance isn’t unfamiliar to most Americans,” Life Happens Executive Director Brian Steiner said. “The challenge is turning that awareness into action. People may think life insurance is something they can deal with later, but waiting can leave the people they love financially vulnerable. Getting started doesn’t have to be complicated, and professional guidance can help you find protection that fits your needs and budget.”
Consider these four ways to make getting life insurance simpler than you thought.
Watch this video to learn more
1. Find a policy that’s a fit.
Roughly 4 in 10 survey respondents reported feeling overwhelmed, anxious or some combination of both about planning for life insurance, with 12% citing thinking it’ll be too expensive as a reason they’ve delayed looking into, buying or updating life insurance.
The good news: There’s a policy that’s right for your current needs. It may be term life insurance, which provides protection for a specific period of time, like to cover a mortgage or tuition for children. There’s also permanent life insurance, which offers lifelong protection, as long as you pay the premiums.
2. Take advantage of digital tools
One-quarter of respondents said they’d be more likely to look into life insurance if they learned it was easier to get than they thought, and digital tools can help make that demand a reality.
It can take as little as two minutes to find out how much you need, for example, with the life insurance needs calculator from the nonprofit Life Happens. Just answer a few simple questions to estimate the amount of life insurance coverage you may need to take care of your family.
3. It’s about protection, not perfection.
Part of the anxiety around life insurance may be the perception that it should be perfect. For more than 1 in 5 survey participants, the plan is to seriously look at it when they feel more financially stable, and another 12% simply said they’ll do it when they’re older.
However, life insurance doesn’t have to check all the boxes for every stage of your life – you can find what works for your family right now then adjust as things change over time.
4. Professional help is available.
Perhaps the biggest hurdle to tackling life insurance is the feeling that you’re in it alone. Overall, 55% of respondents said if they learned life insurance may be easier to get than they expected, they’d be more likely to start the process.
With professional help only a few clicks away, you can rest assured you’re on the path to a life insurance fit that’s right for you by visiting findapro.lifehappens.org.
Photo courtesy of Shutterstock

SOURCE: