Consumer Corner
What are halal mortgages?


Shariq Siddiqui, Indiana University
The growth of “halal mortgages” over the past 20 years has expanded financial access to homeownership for many Muslims. Halal mortgages provide interest-free loans in keeping with Islamic beliefs.
These mortgages are available in over 80 countries that have a significant Muslim population, such as Saudi Arabia, Iran, Malaysia, United Arab Emirates, Kuwait, Qatar, Turkey, Bahrain, Indonesia and Pakistan, where they account for the vast majority of the global US$3.9 trillion Islamic finance economy.
Access to halal mortgages has been growing in the United States. Until 1997, no financial institution was willing to offer halal mortgages, but in 2024, over 25 banks had made them available.
The Conversation asked Shariq Siddiqui, assistant professor and director of the Muslim Philanthropy Initiative at Indiana University, to explain halal mortgages.
What are halal mortgages?
Halal mortgages are a tool of Islamic finance and offer an equitable way to gain homeownership. They emphasize risk-sharing and mutual cooperation with the aim of checking unfair exploitation and wealth accumulation in the hands of a few. In such a system, money is a means of exchange rather than a commodity that generates profit.
What are the religious roots of Islamic finance?
The Muslim holy book, the Quran, and the sayings of the Prophet Muhammad, the Sunnah, prohibit riba, (interest), maisir (speculation) and gharar (uncertainty or uneven risk).
For example, the Quran says, “O you who believe, do not eat up the amounts acquired through ribā (interest), doubled and multiplied. Fear Allah, so that you may be successful.”
Over time, Muslims have sought to develop systems that adhere to these rules. These include bonds that do not receive interest but are based on profit-sharing; socially responsible mutual funds that comply with ethical rules; and insurance that provide protection through a communal fund.
Since World War II, however, monetary policies in the global financial market are largely based upon interest.
How does Islamic financing work in modern context?

In the modern context, Muslims use contract law for economic activity and offer home mortgages without interest. For example, as an attorney, I would develop mortgage contracts that would allow buyers and sellers to transact without interest. This “mortgage” contract would be recorded with the county.
Traditionally, there are three kinds of halal mortgages. In the first, known as ijara, the bank purchases the property and leases it to the homeowner; the homeowner pays rent, principal payments and bank charges; the buyer’s share in the home remains the same until the entire loan is paid off.
Diminishing musharaka is another type of joint ownership plan between the bank and the buyer. The buyer makes principal monthly payments and pays bank charges rather than interest. With each principal payment, the ownership of the buyer increases and the bank’s ownership decreases.
In the third type, murabaha, the bank purchases the home and resells it immediately to the buyer at a higher price – termed as profit. The buyer typically pays a 20% down payment. Thereafter, the buyer makes fixed interest-free payments until the loan is paid off.
What is the availability of halal mortgages in the US?
In 2001 and 2003, respectively, Freddie Mac and Fannie Mae started buying Islamic mortgage products to provide extra liquidity in the U.S. Islamic finance market. These government-backed housing giants work under the conservatorship of the Federal Housing Finance Agency and are one of the principal means of bolstering homeownership in the United States.
These mortgage buyers have grown to become the main investors in Islamic mortgages. For example, Freddie Mac has invested in Guidance Residential, one of the largest halal mortgage companies in the U.S.
What are the advantages?
These systems ensure that there is mutual risk-taking between the bank and the homebuyer. For example, should the homebuyer be unable to keep up payments, their prior principal payments are protected and not consumed by the interest. Furthermore, if the home loses value, both homebuyer and bank proportionally lose out on the principal value of the home.
They require greater transparency on costs, fees and responsibilities; both parties are required to work together and fulfill their obligations.
This reduces the risk of failures like the subprime lending crisis, when banks overvalued homes and financed mortgages that buyers could not afford, leading to a global recession in 2008.
What are the downsides?
Halal mortgages are more expensive and more difficult to enter into, as they require a down payment of at least 20%. Furthermore, they are not available in every state in the United States.
Additionally, many Muslims are unwilling to deposit their money in banks, if those banks are required to pay interest or earn part of their revenue based upon interest.
Shariq Siddiqui, Assistant Professor & Director of the Muslim Philanthropy Initiative, Indiana University
This article is republished from The Conversation under a Creative Commons license. Read the original article.
Welcome to the Consumer Corner section of STM Daily News, your ultimate destination for savvy shopping and informed decision-making! Dive into a treasure trove of insights and reviews covering everything from the hottest toys that spark joy in your little ones to the latest electronic gadgets that simplify your life. Explore our comprehensive guides on stylish home furnishings, discover smart tips for buying a home or enhancing your living space with creative improvement ideas, and get the lowdown on the best cars through our detailed auto reviews. Whether you’re making a major purchase or simply seeking inspiration, the Consumer Corner is here to empower you every step of the way—unlock the keys to becoming a smarter consumer today!

Consumer Corner
5 Smart Ways to Prepare Your Home to Weather Storm Season
By readying your home for storm season in advance, you can prevent minor problems from turning into major damage. Consider these five tips to batten down the hatches when the skies are getting dark.

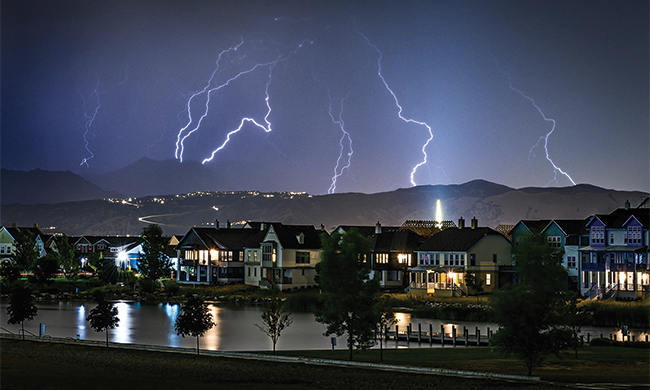
(Feature Impact) Whether your area is prone to thunderstorms, hurricanes, tornadoes or other forms of severe weather, the best time to prepare is before the first raindrop hits. By readying your home for storm season in advance, you can prevent minor problems from turning into major damage.
Consider these five tips to batten down the hatches when the skies are getting dark.
Check Your Roof and Gutters
Your roof has one job – to be a shield against the elements. Don’t wait for a storm to discover you have loose shingles that could fly off in high winds, cracked seals where the roof meets the walls or sagging gutters that aren’t capable of funneling water away from the house. Stay up to date on roof maintenance and clear leaves, twigs and other debris from gutters to prevent clogging.
Trim Trees and Landscaping
Dead trees or weak branches can break and turn into projectiles during storms, potentially causing damage to your house, car or nearby power lines. Next time you have yardwork on the agenda, factor storm preparation into your landscaping plans. Keep trees and bushes trimmed and consider bringing in a professional to assess the health of any trees near your home that could be at risk of toppling.
Strengthen Your Home’s Weak Spots
Windows and doors are some of the most vulnerable places during storms, so pay extra attention to weatherproofing there. Look for any cracks in the glass, check for worn seals or drafty areas and make sure doors close securely and don’t rattle. If you live in an area prone to strong winds or hurricanes, consider upgrading your home with storm shutters for extra peace of mind when debris starts flying.
Turn Your Yard Into a No-Fly Zone
When there’s bad weather in the forecast, you probably aren’t planning to go out and lounge on patio furniture as the skies open up – so pack it up. Secure any items that are too large to bring inside and check around the yard for lightweight items like gardening tools, toys and anything else that could become airborne during strong gusts.
Make a Power Outage Plan
During a storm, nobody wants to fumble around in the dark trying to find batteries for a dead flashlight. Save yourself the trouble by assembling an emergency kit to help your household get by without power if the lines go down. Know where to find flashlights, fresh batteries, power banks to charge your phones, nonperishable food and first-aid supplies or essential medications. If you plan to use a generator, test it and make sure you know how to use it before you need it.
Discover more tips to protect your home at eLivingtoday.com.
Photo courtesy of Unsplash

SOURCE:
🏡 Planning your next home project? Explore expert tips, DIY ideas, product reviews, and the latest home improvement news in Consumer Corner. Share your experiences in the comments and subscribe to the STM Daily News newsletter for practical advice and fresh inspiration delivered straight to your inbox.

Health
5 Babyproofing Tips for Baby Safety Month
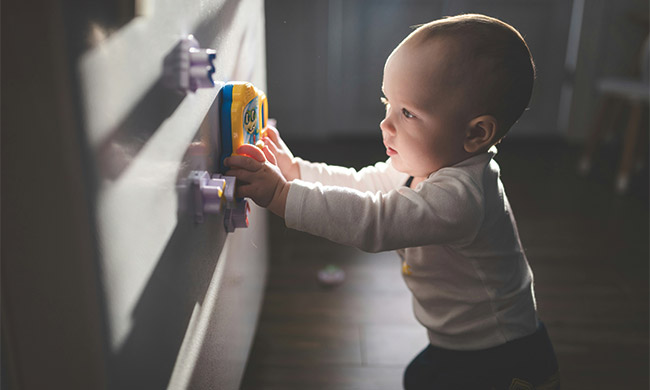
Babyproofing is about anticipating those discoveries before little ones make them. In honor of National Baby Safety Month, consider these tips you can use to make your home safer all year round.
5 Babyproofing Tips for Baby Safety Month
(Feature Impact) Outsmarting a baby can be harder than it sounds – especially when it comes to transforming your home into a safe place for them to explore. Through their eyes, a coffee table becomes a climbing opportunity, a dangling phone charger looks like a teething toy and a cabinet of cleaning supplies could be an exciting travel destination.
Babyproofing is about anticipating those discoveries before little ones make them. In honor of National Baby Safety Month, consider these tips to make your home safer all year round.
Install Gates and Doorknob Covers
Crawling babies and stairs are a bad combination. Make sure the two never have the chance to meet by securely installing safety gates at the top and bottom of staircases to thwart young explorers. Gates or doorknob covers can also block access to other rooms and areas you’d prefer to keep off limits, like kitchens, bathrooms and laundry areas.
Use Safety Latches Wisely
Cabinets and drawers can contain a myriad of dangerous items, from cleaning products to sharp objects and medications. Even if you have rooms gated off, treat safety latches and locked storage receptacles as a second line of defense to make sure babies and toddlers can’t rummage where they shouldn’t.
Stress-Test Furniture
As babies and toddlers transition from crawling to walking, they often try using furniture to pull themselves up. Tall or unstable objects like TV stands, small tables and bookshelves can tip over if they aren’t properly secured. Try giving these objects a shake to see whether they’re easily moveable or wobbly; if so, anchor them to the floor or wall when possible. While you’re at it, check for sharp corners at the right height to bonk little heads and cover them with softer edge protectors.
Cover Outlets and Stow Cords
Electrical outlets can be tempting targets for curious fingers. Outfit them with covers or plastic safety caps, especially if you don’t already have tamper-resistant receptacles with built-in mechanisms to block foreign objects from entering the slots. As you’re going about your outlet audit, pay attention to cords as well. When possible, tuck them away or secure them with cord organizing systems, and block access to objects like lamps where cords can be used for tugging and toppling.
See the World at Their Level
Although it might feel silly, one of the best ways to spot hazards around your home is to scout for them from a baby’s perspective. Try getting as close to the floor as you can then look around each room for anything that could interest a young child and pose potential danger. In particular, keep an eye out for small objects that could become choking hazards, like dropped coins, batteries or loose toy pieces.
As children grow, so do the needs of your space. Visit eLivingtoday.com for more ideas on designing your home to fit your family.
Photo courtesy of Unsplash

SOURCE:
💪 Your health journey starts here! Explore the latest health news, fitness tips, wellness trends, and healthy living advice. Share your thoughts in the comments and subscribe to the STM Daily News newsletter to stay informed and inspired every day.
Economy
U.S. Consumer Confidence Slips as Americans Grow More Cautious About the Future
U.S. consumer confidence edged lower in August as Americans became more pessimistic about jobs, income and business conditions over the next six months, despite improved views of the current economy.

NEW YORK — U.S. consumer confidence edged lower in August as Americans expressed greater concern about future business conditions, jobs and household income, even as their assessment of the current economy improved.
The Conference Board reported that its Consumer Confidence Index fell 0.8 points to 89.4 in August, down from 90.2 in July.
The relatively small decline, however, masks a widening gap between how consumers view conditions today and what they expect in the months ahead.
The Present Situation Index, which measures consumers’ assessment of current business and labor market conditions, climbed 6.8 points to 121.2, reversing three consecutive months of declines.
Meanwhile, the Expectations Index, which measures the short-term outlook for income, business and employment conditions, dropped 5.8 points to 68.2.
“Consumer confidence moderated slightly in August for a second consecutive month,” Dana M. Peterson, chief economist at The Conference Board, said in the organization’s Aug. 25 release.
Jobs Look Better Today — But Consumers Worry About Tomorrow
Americans’ perceptions of the current labor market improved considerably during August. About 27% said jobs were plentiful, up from 24.4% in July, while 19.5% said jobs were hard to get, down from 21.7%.
The outlook for the next six months was considerably weaker.
Only 14.6% expected more jobs to become available, compared with 16.4% in July. At the same time, 26.1% expected fewer jobs.
Consumers were also less optimistic about their incomes. About 17.6% expected their income to increase, down from 19.5% in July, while 13.8% expected their income to decline.
Prices Remain on Consumers’ Minds
Inflation continues to influence how Americans feel about the economy. According to The Conference Board, consumers’ written responses frequently mentioned prices, oil and gasoline, food and groceries, trade, jobs, and war or conflict.
Average and median expectations for inflation over the next 12 months also increased slightly.
Interest rates remain another concern. More than six in 10 consumers — 61.3% — expected interest rates to rise over the next year, although that was slightly lower than the 62% recorded in July.
Consumers Are Still Planning to Spend
The softer outlook hasn’t eliminated Americans’ willingness to make purchases.
Auto-buying expectations remained strong on a six-month moving-average basis, while homebuying expectations declined slightly in August but remained on a longer-term upward trend after hitting decade lows in early 2024.
Restaurants, bars and takeout; utilities; and streaming, internet and mobile services ranked among consumers’ leading planned service expenses.
Consumers were less enthusiastic about discretionary activities including movies, personal-travel hotels, airfare, amusement parks, museums and historical sites.
Why It Matters
The August numbers paint a mixed picture of the American consumer.
People are seeing some improvement in the economy they are experiencing today, particularly in the labor market. But their expectations for the next six months are becoming noticeably more cautious.
That divide matters because consumer spending represents a major part of U.S. economic activity. If concerns about employment, inflation and household income begin translating into reduced spending, weakening confidence could eventually become more significant for the broader economy.
For now, the August survey suggests Americans haven’t stopped spending — but they’re increasingly keeping an eye on what may be coming next.
The preliminary August Consumer Confidence Survey was conducted online for The Conference Board by Toluna. The survey period was Aug. 3–16, 2026.
Source: The Conference Board, August 2026 Consumer Confidence Survey®, released Aug. 25, 2026.
STM Daily News Economy News Brief
Sources
- The Conference Board — U.S. Consumer Confidence, August 2026 — Primary source for the August Consumer Confidence Index, Present Situation Index and Expectations Index.
- The Conference Board — Consumer Confidence Survey & Data — Consumer confidence survey information, methodology and release schedule.
Related Economic Data
- Bureau of Economic Analysis — Consumer Spending — Official U.S. data tracking personal consumption expenditures. Consumer spending increased 0.2% in July 2026.
- BEA — Personal Income and Outlays, July 2026 — Tracks household income, disposable income, consumer spending and saving.
- Bureau of Labor Statistics — Consumer Price Index — Official inflation data. The July 2026 CPI was up 3.4% from a year earlier; August CPI is scheduled for release September 11.
- Federal Reserve — Consumer Credit — Federal Reserve data covering revolving and nonrevolving consumer credit.