Connect with us

Business and Finance

Companies haven’t stopped hiring, but they’re more cautious, according to the 2025 College Hiring Outlook Report

Published

on

College Hiring Outlook Report
Recent college grads face a tough job market in 2025, but employers are still hiring.
sturti/E+ via Getty Images

Murugan Anandarajan, Drexel University

Companies haven’t stopped hiring, but they’re more cautious, according to the 2025 College Hiring Outlook Report

Every year, I tell my students in my business analytics class the same thing: “Don’t just apply for a job. Audition for it.”

This advice seems particularly relevant this year. In today’s turbulent economy, companies are still hiring, but they’re doing it a bit more carefully. More places are offering candidates short-term work experiences like internships and co-op programs in order to evaluate them before making them full-time offers.

This is just one of the findings of the 2025 College Hiring Outlook Report. This annual report tracks trends in the job market and offers valuable insights for both job seekers and employers. It is based on a national survey conducted in September 2024, with responses from 1,322 employers spanning all major industries and company sizes, from small firms to large enterprises. The survey looks at employer perspectives on entry-level hiring trends, skills demand and talent development strategies.

I am a professor of information systems at Drexel University’s LeBow College of Business in Philadelphia, and I co-authored this report along with a team of colleagues at the Center for Career Readiness.

Here’s what we found:

Employers are rethinking talent pipelines

Only 21% of the 1,322 employers we surveyed rated the current college hiring market as “excellent” or “very good,” which is a dramatic drop from 61% in 2023. This indicates that companies are becoming increasingly cautious about how they recruit and select new talent.

While confidence in full-time hiring has declined, employers are not stepping away from hiring altogether. Instead, they’re shifting to paid and unpaid internships, co-ops and contract-to-hire roles as a less risky route to identify talent and “de-risk” full-time hiring.

Employers we surveyed described internships as a cost-effective talent pipeline, and 70% told us they plan to maintain or increase their co-op and intern hiring in 2025. At a time when many companies are tightening their belts, hiring someone who’s already proved themselves saves on onboarding reduces turnover and minimizes potentially costly mishires.

For job seekers, this makes every internship or short-term role more than a foot in the door. It’s an extended audition. Even with the general market looking unstable, interest in co-op and internship programs appears steady, especially among recent graduates facing fewer full-time opportunities.

These programs aren’t just about trying out a job. They let employers see if a candidate shows initiative, good judgment and the ability to work well on a team, which we found are traits employers value even more than technical skills.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

What employers want

We found that employers increasingly prioritize self-management skills like adaptability, ethical reasoning and communication over technical skills such as digital literacy and cybersecurity. Employers are paying attention to how candidates behave during internships, how they take feedback, and whether they bring the mindset needed to grow with the company.

This reflects what I have observed in classrooms and in conversations with hiring managers: Credentials matter, but what truly sets candidates apart is how they present themselves and what they contribute to a company.

Based on co-op and internship data we’ve collected at Drexel, however, many students continue to believe that technical proficiency is the key to getting a job.

In my opinion, this disconnect reveals a critical gap in expectations: While students focus on hard skills to differentiate themselves, employers are looking for the human skills that indicate long-term potential, resilience and professionalism. This is especially true in the face of economic uncertainty and the ambiguous, fast-changing nature of today’s workplace.

Technology is changing how hiring happens

Employers also told us that artificial intelligence is now central to how both applicants and employers navigate the hiring process.

Some companies are increasingly using AI-powered platforms to transform their hiring processes. For example, Children’s Hospital of Philadelphia uses platforms like HireVue to conduct asynchronous video interviews. HR-focused firms like Phenom and JJ Staffing Services also leverage technologies such as AI-based resume ranking, automated interview scheduling and one-way video assessments.

Not only do these tools speed up the hiring process, but they also reshape how employers and candidates interact. In our survey, large employers said they are increasingly relying on AI tools like resume screeners and one-way video interviews to manage large numbers of job applicants. As a result, the candidate’s presence, clarity in communication and authenticity are being evaluated even before a human recruiter becomes involved.

At the same time, job seekers are using generative AI tools to write cover letters, practice interviews or reformat resumes. These tools can help with preparation, but overreliance on them can backfire. Employers want authenticity, and many employers we surveyed mentioned they notice when applications seem overly robotic.

In my experience as a professor, the key is teaching students to use AI to enhance their effort and not replace it. I encourage them to leverage AI tools but always emphasize that the final output and the impression it makes should reflect their own thinking and professionalism. The bottom line is that hiring is still a human decision, and the personal impression you make matters.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

This isn’t just about new grads

While our research focuses on early-career hiring, these findings apply to other audiences as well, such as career changers, returning professionals and even mid-career workers. These workers are increasingly being evaluated on their adaptability, behavior and collaborative ability – not just their experience.

Many companies now offer project-based assignments and trial roles that let them evaluate performance before making a permanent hire.

At the same time, employers are investing in internal reskilling and upskilling programs. Reskilling refers to training workers for entirely new roles, often in response to job changes or automation, while upskilling means helping employees deepen their current skills to stay effective and advance in their existing roles. Our report indicates that approximately 88% of large companies now offer structured upskilling and reskilling programs. For job seekers and workers alike, staying competitive means taking the initiative and demonstrating a commitment to learning and growth.

Show up early, and show up well

So what can students, or anyone entering or reentering the workforce, do to prepare?

  • Start early. Don’t wait until senior year. First- and second-year internships are growing in importance.
  • Sharpen your soft skills. Communication, time management, problem-solving and ethical behavior are top priorities for employers.
  • Understand where work is happening. Over 50% of entry-level jobs are fully in-person. Only 4% are fully remote. Show up ready to engage.
  • Use AI strategically. It’s a useful tool for research and practice, not a shortcut to connection or clarity.
  • Stay curious. Most large employers now offer reskilling or upskilling opportunities – and they expect employees to take initiative.

One of the clearest takeaways from this year’s report is that hiring is no longer a one-time decision. It’s a performance process that often begins before an interview is even scheduled.

Whether you’re still in school, transitioning in your career or returning to the workforce after a break, the same principle applies: Every opportunity is an audition. Treat it like one.

Murugan Anandarajan, Professor of Decision Sciences and Management Information Systems, Drexel University

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Continue Reading
Advertisement SodaStream USA, inc

Health and Life Insurance

Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think

Life is the most valuable thing you have – and like all valuable things, it should be insured. Even thinking about life insurance can be stressful, so it’s one of those things that’s easy to put off and tell yourself you’ll do another day. Consider these four ways to make getting life insurance simpler than you thought.

Published

on

Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think

Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think

(Feature Impact) Life is the most valuable thing you have – and like all valuable things, it should be insured. Even thinking about life insurance can be stressful, so it’s one of those things that’s easy to put off and tell yourself you’ll do another day.

If that’s how you feel, you aren’t alone. According to the 2026 Life Happens Life Insurance Survey, nearly half (46%) of U.S. adults have getting life insurance on their to-do list but plan to deal with it later or not at all. Confusion, procrastination and cost concerns are among the main reasons people kick this can down the road, according to 45% of respondents.

Yet the survey also uncovered an interesting disconnect: 69% of Americans said they personally know someone who had life insurance or whose family used a life insurance policy, most often a parent or parent figure (33%), but still haven’t made getting coverage a priority.

“Life insurance isn’t unfamiliar to most Americans,” Life Happens Executive Director Brian Steiner said. “The challenge is turning that awareness into action. People may think life insurance is something they can deal with later, but waiting can leave the people they love financially vulnerable. Getting started doesn’t have to be complicated, and professional guidance can help you find protection that fits your needs and budget.”

Consider these four ways to make getting life insurance simpler than you thought.

Watch this video to learn more

https://youtube.com/watch?v=ZaCW8BUQkIs%3Fsi%3DhnRfe5n-67h4VyxQ%26controls%3D0
1. Find a policy that’s a fit.

Roughly 4 in 10 survey respondents reported feeling overwhelmed, anxious or some combination of both about planning for life insurance, with 12% citing thinking it’ll be too expensive as a reason they’ve delayed looking into, buying or updating life insurance.

The good news: There’s a policy that’s right for your current needs. It may be term life insurance, which provides protection for a specific period of time, like to cover a mortgage or tuition for children. There’s also permanent life insurance, which offers lifelong protection, as long as you pay the premiums.

2. Take advantage of digital tools

One-quarter of respondents said they’d be more likely to look into life insurance if they learned it was easier to get than they thought, and digital tools can help make that demand a reality.

It can take as little as two minutes to find out how much you need, for example, with the life insurance needs calculator from the nonprofit Life Happens. Just answer a few simple questions to estimate the amount of life insurance coverage you may need to take care of your family.

3. It’s about protection, not perfection.

Part of the anxiety around life insurance may be the perception that it should be perfect. For more than 1 in 5 survey participants, the plan is to seriously look at it when they feel more financially stable, and another 12% simply said they’ll do it when they’re older.

However, life insurance doesn’t have to check all the boxes for every stage of your life – you can find what works for your family right now then adjust as things change over time.

Advertisement
Get More From A Face Cleanser And Spa-like Massage
4. Professional help is available.

Perhaps the biggest hurdle to tackling life insurance is the feeling that you’re in it alone. Overall, 55% of respondents said if they learned life insurance may be easier to get than they expected, they’d be more likely to start the process.

With professional help only a few clicks away, you can rest assured you’re on the path to a life insurance fit that’s right for you by visiting findapro.lifehappens.org.

Photo courtesy of Shutterstock collect?v=1&tid=UA 482330 7&cid=1955551e 1975 5e52 0cdb 8516071094cd&sc=start&t=pageview&dl=http%3A%2F%2Ftrack.familyfeatures track

SOURCE:

Life Happens

Continue Reading

Economy

Bridging the Gap Between Military Experience and Civilian Careers: 5 Tips for Veterans

Published

on

Bridging the Gap Between Military Experience and Civilian Careers: 5 Tips for Veterans

(Feature Impact) Every year, approximately 200,000 service men and women transition from military life to corporate America. Finding the right civilian career is a transition, but it’s an opportunity to leverage military leadership and mission-driven talent.

Traditional hiring processes often focus on conventional resumes, but forward-thinking organizations recognize military experience as a competitive advantage in today’s workforce. The resilience, integrity and adaptability of America’s veterans and military families make them uniquely positioned to drive growth and innovation in their communities.

“Veterans bring unmatched discipline, adaptability and a results-driven mindset that directly translates to high-impact corporate careers,” said Drew Matheson, senior director at Capital One’s Commercial Bank and retired U.S. Army infantry officer. “While military experience doesn’t always fit perfectly on a traditional paper resume, employers like Capital One who know how to decode these unique leadership skills are able to unlock an incredible pipeline of proven performers.”

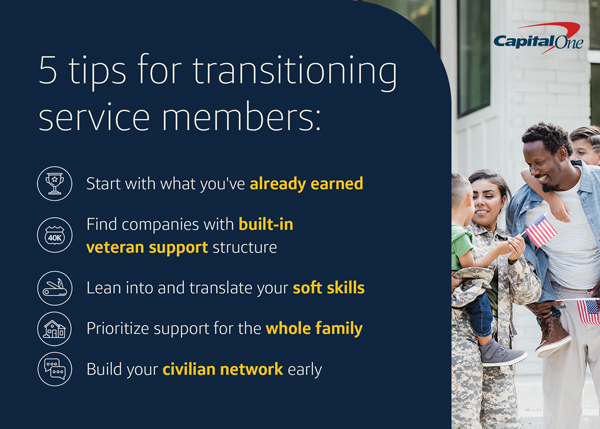
To help transitioning service members successfully navigate this career pivot, military community leaders at Capital One offer these five essential tips for service members entering the civilian workforce:18007 B detail embed2

Start With What You’ve Already Earned

Opportunity starts with preparation. Beyond the well-known Post-9/11 GI Bill, which can cover tuition, housing and books, transitioning service members can look into vocational rehab or the SkillBridge program, which allows them to do civilian internships during the last 180 days of service. Many employers also offer internal tuition reimbursement programs. Taking the time to proactively map out these benefits ensures you aren’t leaving valuable opportunities or money on the table.

Find Employers with Veteran Support Structures

With almost half of veterans leaving their first post-military job within a year, according to research published by the Institute for Veterans and Military Families and VetAdvisor, finding the right culture and community is key to a successful transition. Look for employers with active veteran networks and dedicated mentorship.

For example, Capital One’s Salute Business Resource Group serves as a thriving internal community of more than 6,000 members, offering peer support, year-round professional development and mentorship for veterans, reservists and military spouses. Additionally, partner organizations like Hiring Our Heroes provide career workshops, fellowships and job fairs to ensure you’re employment-ready from day one.

Lean Into and Translate Your Soft Skills

Veterans bring a distinct competitive advantage to the applicant pool. You should confidently lean into the cross-functional “soft skills” learned in the line of duty such as risk management, crisis resolution and building trust under high-pressure scenarios.

The trick is translating these capabilities out of military jargon on your resume. Swap military terms like “NCOIC” for “Operations Manager” or “commanded” for “directed.” To make this easier, look for military-friendly employers that employ dedicated military recruiters who specialize in decoding military resumes to align skills with the right roles.

Prioritize Support for the Whole Family

Military service is a family commitment, and the transition out of uniform affects everyone. Military spouses often face unique career hurdles, including frequent relocations and employment gaps. When evaluating employers, look for companies that offer holistic benefits and flexible structures.

For example, Capital One, recognized by “U.S. Veterans Magazine” as a Top Veteran Employer and Top Military Spouse Employer, actively supports military spouses and families through dedicated spouse hiring initiatives and internal support mechanisms. Furthermore, look for organizations that support continued military training and active-duty leave, ensuring military associates never have to choose between their service and their careers.

Build Your Civilian Network Early

In the military, your network is built in. In the civilian world, you have to cultivate it. Long before your terminal leave begins, connect with veterans who work at companies you admire. Reach out for brief, 15-minute informational interviews to learn about their transition journeys rather than simply asking for a job. With more than 70% of civilian jobs filled through networking, according to estimates from Career Horizons, making organic connections early is a powerful tool for getting your foot in the door.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

To find additional resources and learn more about how to support the hiring of veterans and military spouses, visit CapitalOneCareers.com/Military.

Photo courtesy of Shutterstock collect?v=1&tid=UA 482330 7&cid=1955551e 1975 5e52 0cdb 8516071094cd&sc=start&t=pageview&dl=http%3A%2F%2Ftrack.familyfeatures track

SOURCE:

Capital One

Start Your Morning Informed

Get the STM Morning Brief delivered to your inbox every weekday with breaking news, transportation updates, technology, science, and trending stories.

STM News Brief Ad 2

We don’t spam! Read our privacy policy for more info.

Continue Reading

financial wellness

Personal bankruptcy filings are soaring in 2026, signaling growing economic distress

Personal bankruptcy filings are climbing as inflation, high interest rates and mounting household debt strain American consumers. Although bankruptcy can provide a fresh start, financial recovery may take decades.

Published

on

An outstretched arm pokes through a pile of paper, holding a white flag signaling surrender. bankruptcy
Declaring bankruptcy when you’re drowning in debt should be a last resort. thewet/iStock via Getty Images Plus

Jay L. Zagorsky, Boston University

The number of Americans who file for bankruptcy is growing. More than 500,000 people took this step in 2025, nearly 50% more than in 2022. And the numbers have kept on climbing, with a 12% jump in June 2026 from a year earlier as many consumers struggled to pay their bills.

I am a business school professor who has researched bankruptcies and whether, when you are at the end of your financial rope, bankruptcy helps or hurts.

I became interested in the subject while in graduate school. Not because of any courses I took, but because I ran out of money. While I was in grad school, my wife, who was keeping the family afloat, unexpectedly lost her job at the very moment our savings went to zero.

Ultimately, we didn’t declare bankruptcy, and I’ll explain later what we did to avoid it. But this near brush with that fate sparked my long-term interest in this predicament that befalls many American consumers who find themselves financially stressed out.

What’s personal bankruptcy?

Bankruptcy is a legal process for people who can’t pay their debts. Because it usually requires liquidating their assets or entering a repayment plan, Americans generally turn to it as a last resort. To declare bankruptcy you first file a petition with a federal court, which appoints a trustee to oversee your case.

But bankruptcy does not discharge all debts.

There are 19 types of debts that even bankruptcy will not wipe out. Some of the bigger categories are alimony, child support and most taxes. Student loans can be wiped out, but getting that done is difficult and it’s not an automatic part of bankruptcy proceedings.

2 conflicting goals

U.S. bankruptcy law has two big goals that contradict each other.

The first is to give honest individual debtors a “fresh start.” The process ideally reduces or eliminates enough of their debt to make it possible to earn, spend, borrow and repay money like people with a more typical financial life. In other words, personal bankruptcy can take the financial noose off debtors’ necks.

The second is to ensure that creditors get repaid as much as possible for their loans. When someone declares bankruptcy, some or maybe all of their creditors don’t get their money back. In 2024, the Americans who filed for bankruptcy had about US$75 billion in assets, but they owed their creditors about $86 billion – $11 billion more.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

States and the federal government make different trade-offs between these goals. As a result there are very different limits on how much equity – the difference between market value and what you owe – debtors can keep in their primary homes and personal property after they declare bankruptcy.

Some states are quite lenient. For example, Texas bankruptcy law doesn’t limit the amount of equity in a home at all. That helps debtors get back on their feet.

Other states are extremely strict in this regard. Arkansas limits home equity after personal bankruptcy to $800, and Kentucky restricts it to $5,000. This helps creditors: Lenders can force a debtor’s house to be sold and keep much of the equity the debtor built up.

Likewise, laws protecting vehicles and other kinds of personal property belonging to people who declare bankruptcy vary widely.

2 types of personal bankruptcy

People declaring bankruptcy typically file using either Chapter 7 or Chapter 13 of the federal bankruptcy code.

About 2 in 3 people use Chapter 7, a form of financial liquidation. The bankruptcy court appoints a trustee, who then sells off all of a person’s possessions, except what is covered by the various exemptions.

The trustee then gives creditors whatever money is left after the sale. In exchange for giving up most of what someone owns, filing Chapter 7 wipes out almost all debts and gives them a fresh financial start.

For people earning moderate to high incomes and whose debts are less than $2.75 million, bankruptcy courts make them use Chapter 13.

Chapter 13 is a slower-moving process. Creditors are paid over three to five years from a person’s earnings. Debtors keep enough of their wages to cover necessary living expenses, but all other disposable income goes to creditors. Chapter 13 allows people to save their homes from foreclosure and keep their vehicles.

A man in a green suit leans down to pull someone else in a suit out of a manhole.
Filing for bankruptcy is a legal process, so it helps to hire a lawyer to handle the paperwork. D_BANK/DigitalVision Vectors via Getty Images

Bankruptcy filing rising after decline

The number of personal bankruptcies filed annually fell sharply for more than a decade before the recent uptick, hitting a low of about 368,000 in 2022, down from about 1.5 million in 2010.

That number has climbed steadily since 2022.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

A 2005 law called the Bankruptcy Abuse Prevention and Consumer Protection Act sparked the earlier decline. Its goal was to make declaring bankruptcy harder and more expensive. Many creditors pushed for these changes because they felt some individuals were abusing the system.

The changes introduced income limits for eligibility to declare Chapter 7 bankruptcy. It also required people to get credit counseling before filing to see whether there was any way they could avoid bankruptcy. It also added a new obligation: Americans now take a course in financial management after they file for bankruptcy to reduce the chance of future money troubles.

One interesting study regarding the legislation’s impact found that it lowered credit card interest rates, but it also prevented some people without health insurance from wiping out their medical debts.

The 2005 changes caused the number of personal bankruptcies to plunge. That ended with the Great Recession, which lasted from late 2007 until mid-2009.

This economic downturn pushed up the number of bankruptcies dramatically. But then the number fell from 2010 until 2022, as the Great Recession’s impact gradually receded. The decline continued into the early 2020s because the stimulus checks and more generous unemployment insurance payments the government provided at the height of the COVID-19 pandemic helped keep millions of U.S. consumers afloat.

The numbers began to rise again in 2022 as American consumers began facing increasing stress from income that has not kept pace with inflation and a sharp jump in credit card interest rates.

Lasting changes

Bankruptcy stays on your credit report for up to 10 years. After that, creditors are supposed to treat people who filed for it like anyone else. A study I worked on with law professor Lois Lupica tracked what happened over two decades to both people who had and had not declared bankruptcy. We wanted to see whether those who had filed for bankruptcy really got out of their financial hole.

Our findings were a good news, bad news story. The good news was that bankruptcy was not causing permanent financial stigma. The average person who declared bankruptcy eventually caught up financially with their peers who hadn’t.

The bad news was that it took 15-25 years to recover in almost all financial dimensions. This is longer than those 10 years that the bankruptcy filing stays on your credit report.

In short, we determined that bankruptcy does give people a fresh start, but getting that reprieve takes longer than the law’s intent.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

Strategies that can stave off bankruptcy

My wife and I avoided bankruptcy primarily by doing two things.

First, we switched to using cash for most of our day-to-day purchases. When our wallets were empty, we were done spending. I talk more about this in my 2025 book “The Power of Cash.”

Second, we contacted the financial company where we owed our biggest monthly payment. After providing proof of financial hardship, they were surprisingly flexible.

If these two steps are not enough for you, the next step is to consult an attorney who specializes in bankruptcy law. While there are lots of things most people can competently do on their own, filing for bankruptcy is not one of them.

Jay L. Zagorsky, Associate Professor of Business, Boston University

This article is republished from The Conversation under a Creative Commons license. Read the original article.
See What’s Happening Now!

Continue Reading

Trending