financial wellness
Home buyers with lower credit scores pay an extra $104,000 in mortgage costs

Last Updated on May 16, 2024 by Daily News Staff
- Improving your credit score can save hundreds a month on your mortgage
- A borrower with a “fair” credit score could pay $103,626 more over the life of a 30-year mortgage for the same home than an otherwise identical borrower with an “excellent” score would
- Barriers to housing that result from credit issues are often more profound for people of color
SEATTLE, July 28, 2022 /PRNewswire/ — Elevated home prices and rising interest rates are feeding into housing affordability woes for potential buyers, especially those with lower credit scores. A new Zillow analysis shows that, nationally, buyers with “fair” credit could be paying up to $288 more on their monthly mortgage payment than those with “excellent” credit.
Today’s home shoppers can expect to pay around 62% more per month to buy a typically priced U.S. home than they would have a year ago. Zillow examined credit scores against current mortgage rates and found that such monthly cost increases are exacerbated for millions of Americans with low credit scores or less than perfect credit histories.
A borrower with an “excellent” credit score — between 760 and 850 — can qualify for a 30-year fixed-rate mortgage with a 5.099% interest rate1. For the same loan, a similar borrower with a “fair” credit score — between 620 and 639 — qualifies for a 6.688% rate1. This equates to a $288 difference in monthly mortgage payments and nearly $103,626 in interest over the life of a 30-year fixed loan, based on the current price of a typical U.S. home ($354,165)2.
“When you are thinking about buying a home, the best first step you can take is to fully understand your financial picture, what you can afford and your outstanding debts or obligations,” said Libby Cooper, Zillow Home Loans vice president. “If you find you have low credit, take realistic steps to improve your credit score by doing things like disputing possible report errors and paying down as much debt as possible. This could increase the amount of home loan you qualify for.”
The chart below illustrates how a buyer’s credit profile plays an important role in how much a home ultimately costs. Buyers who make raising their credit score part of their initial steps in the home-buying process typically have more buying power and lower monthly payments.
The cost of buying a typically priced U.S. home based on credit scores3FICO® Score Estimated Annual
Percentage Rate1Monthly Payment Total Loan Cost 760–850 5.099 % $1,538 $553,743 700–759 5.321 % $1,557 $567,739 680–699 5.498 % $1,608 $579,014 660–679 5.712 % $1,647 $592,782 640–659 6.142 % $1,725 $620,882 620–639 6.688 % $1,826 $657,369
There is a direct correlation between credit security — having a strong credit history and structural access to credit offerings — and higher homeownership rates. The homeownership rate is lower in counties that are more “credit insecure,” meaning they are home to high numbers of residents with poor or no credit history. That cuts off millions — particularly Black and Latinx residents — from the wealth-building advantages of homeownership. Additionally, Black applicants are denied a mortgage at a rate 84% higher than white applicants, and credit history is the most common reason cited for those denials. Limited traditional financial services in Black and other communities of color are a significant factor in the lack of credit history and the inability to build a high credit score.
Fannie Mae and Freddie Mac recently adopted policies that include timely rent payments in their automated underwriting systems. Lenders and brokers can submit bank account data (with borrower permission) to identify 12 months of prompt rent payments to help potential borrowers qualify for a mortgage.
“While inclusion of timely rent payments doesn’t change a borrower’s credit score, it can have a positive impact on how lenders view a borrower’s credit worthiness. This move shows how effective policy changes can help consumers build a strong financial foundation that unlocks homeownership,” said Cooper.
About Zillow Group:
Zillow Group, Inc. (NASDAQ: Z and ZG) is reimagining real estate to make it easier to unlock life’s next chapter. As the most visited real estate website in the United States, Zillow® and its affiliates offer customers an on-demand experience for selling, buying, renting or financing with transparency and ease.
Zillow Group’s affiliates and subsidiaries include Zillow®, Zillow Offers®, Zillow Premier Agent®, Zillow Home Loans™, Zillow Closing Services™, Zillow Homes, Inc., Trulia®, Out East®, ShowingTime®, Bridge Interactive®, dotloop®, StreetEasy® and HotPads®. Zillow Home Loans, LLC is an Equal Housing Lender, NMLS #10287 (www.nmlsconsumeraccess.org).
1 Based on the FICO Loan Savings Calculator on myfico.com. Rates current as of July 26, 2022.
2 According to the Zillow Home Value Index.
3 Loan calculations assume a 20% down payment on a home cost of $354,165 with a 30-year fixed mortgage. Total loan cost includes the loan value and interest cost over the life of the loan.
SOURCE Zillow


(Feature Impact) Every year, approximately 200,000 service men and women transition from military life to corporate America. Finding the right civilian career is a transition, but it’s an opportunity to leverage military leadership and mission-driven talent.
Traditional hiring processes often focus on conventional resumes, but forward-thinking organizations recognize military experience as a competitive advantage in today’s workforce. The resilience, integrity and adaptability of America’s veterans and military families make them uniquely positioned to drive growth and innovation in their communities.
“Veterans bring unmatched discipline, adaptability and a results-driven mindset that directly translates to high-impact corporate careers,” said Drew Matheson, senior director at Capital One’s Commercial Bank and retired U.S. Army infantry officer. “While military experience doesn’t always fit perfectly on a traditional paper resume, employers like Capital One who know how to decode these unique leadership skills are able to unlock an incredible pipeline of proven performers.”
To help transitioning service members successfully navigate this career pivot, military community leaders at Capital One offer these five essential tips for service members entering the civilian workforce: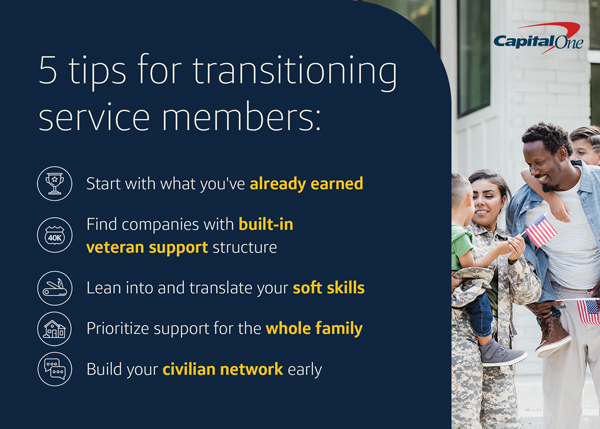
Start With What You’ve Already Earned
Opportunity starts with preparation. Beyond the well-known Post-9/11 GI Bill, which can cover tuition, housing and books, transitioning service members can look into vocational rehab or the SkillBridge program, which allows them to do civilian internships during the last 180 days of service. Many employers also offer internal tuition reimbursement programs. Taking the time to proactively map out these benefits ensures you aren’t leaving valuable opportunities or money on the table.
Find Employers with Veteran Support Structures
With almost half of veterans leaving their first post-military job within a year, according to research published by the Institute for Veterans and Military Families and VetAdvisor, finding the right culture and community is key to a successful transition. Look for employers with active veteran networks and dedicated mentorship.
For example, Capital One’s Salute Business Resource Group serves as a thriving internal community of more than 6,000 members, offering peer support, year-round professional development and mentorship for veterans, reservists and military spouses. Additionally, partner organizations like Hiring Our Heroes provide career workshops, fellowships and job fairs to ensure you’re employment-ready from day one.
Lean Into and Translate Your Soft Skills
Veterans bring a distinct competitive advantage to the applicant pool. You should confidently lean into the cross-functional “soft skills” learned in the line of duty such as risk management, crisis resolution and building trust under high-pressure scenarios.
The trick is translating these capabilities out of military jargon on your resume. Swap military terms like “NCOIC” for “Operations Manager” or “commanded” for “directed.” To make this easier, look for military-friendly employers that employ dedicated military recruiters who specialize in decoding military resumes to align skills with the right roles.
Prioritize Support for the Whole Family
Military service is a family commitment, and the transition out of uniform affects everyone. Military spouses often face unique career hurdles, including frequent relocations and employment gaps. When evaluating employers, look for companies that offer holistic benefits and flexible structures.
For example, Capital One, recognized by “U.S. Veterans Magazine” as a Top Veteran Employer and Top Military Spouse Employer, actively supports military spouses and families through dedicated spouse hiring initiatives and internal support mechanisms. Furthermore, look for organizations that support continued military training and active-duty leave, ensuring military associates never have to choose between their service and their careers.
Build Your Civilian Network Early
In the military, your network is built in. In the civilian world, you have to cultivate it. Long before your terminal leave begins, connect with veterans who work at companies you admire. Reach out for brief, 15-minute informational interviews to learn about their transition journeys rather than simply asking for a job. With more than 70% of civilian jobs filled through networking, according to estimates from Career Horizons, making organic connections early is a powerful tool for getting your foot in the door.
To find additional resources and learn more about how to support the hiring of veterans and military spouses, visit CapitalOneCareers.com/Military.
Photo courtesy of Shutterstock

SOURCE:
financial wellness
Personal bankruptcy filings are soaring in 2026, signaling growing economic distress
Personal bankruptcy filings are climbing as inflation, high interest rates and mounting household debt strain American consumers. Although bankruptcy can provide a fresh start, financial recovery may take decades.

Jay L. Zagorsky, Boston University
The number of Americans who file for bankruptcy is growing. More than 500,000 people took this step in 2025, nearly 50% more than in 2022. And the numbers have kept on climbing, with a 12% jump in June 2026 from a year earlier as many consumers struggled to pay their bills.
I am a business school professor who has researched bankruptcies and whether, when you are at the end of your financial rope, bankruptcy helps or hurts.
I became interested in the subject while in graduate school. Not because of any courses I took, but because I ran out of money. While I was in grad school, my wife, who was keeping the family afloat, unexpectedly lost her job at the very moment our savings went to zero.
Ultimately, we didn’t declare bankruptcy, and I’ll explain later what we did to avoid it. But this near brush with that fate sparked my long-term interest in this predicament that befalls many American consumers who find themselves financially stressed out.
What’s personal bankruptcy?
Bankruptcy is a legal process for people who can’t pay their debts. Because it usually requires liquidating their assets or entering a repayment plan, Americans generally turn to it as a last resort. To declare bankruptcy you first file a petition with a federal court, which appoints a trustee to oversee your case.
But bankruptcy does not discharge all debts.
There are 19 types of debts that even bankruptcy will not wipe out. Some of the bigger categories are alimony, child support and most taxes. Student loans can be wiped out, but getting that done is difficult and it’s not an automatic part of bankruptcy proceedings.
2 conflicting goals
U.S. bankruptcy law has two big goals that contradict each other.
The first is to give honest individual debtors a “fresh start.” The process ideally reduces or eliminates enough of their debt to make it possible to earn, spend, borrow and repay money like people with a more typical financial life. In other words, personal bankruptcy can take the financial noose off debtors’ necks.
The second is to ensure that creditors get repaid as much as possible for their loans. When someone declares bankruptcy, some or maybe all of their creditors don’t get their money back. In 2024, the Americans who filed for bankruptcy had about US$75 billion in assets, but they owed their creditors about $86 billion – $11 billion more.
States and the federal government make different trade-offs between these goals. As a result there are very different limits on how much equity – the difference between market value and what you owe – debtors can keep in their primary homes and personal property after they declare bankruptcy.
Some states are quite lenient. For example, Texas bankruptcy law doesn’t limit the amount of equity in a home at all. That helps debtors get back on their feet.
Other states are extremely strict in this regard. Arkansas limits home equity after personal bankruptcy to $800, and Kentucky restricts it to $5,000. This helps creditors: Lenders can force a debtor’s house to be sold and keep much of the equity the debtor built up.
Likewise, laws protecting vehicles and other kinds of personal property belonging to people who declare bankruptcy vary widely.
2 types of personal bankruptcy
People declaring bankruptcy typically file using either Chapter 7 or Chapter 13 of the federal bankruptcy code.
About 2 in 3 people use Chapter 7, a form of financial liquidation. The bankruptcy court appoints a trustee, who then sells off all of a person’s possessions, except what is covered by the various exemptions.
The trustee then gives creditors whatever money is left after the sale. In exchange for giving up most of what someone owns, filing Chapter 7 wipes out almost all debts and gives them a fresh financial start.
For people earning moderate to high incomes and whose debts are less than $2.75 million, bankruptcy courts make them use Chapter 13.
Chapter 13 is a slower-moving process. Creditors are paid over three to five years from a person’s earnings. Debtors keep enough of their wages to cover necessary living expenses, but all other disposable income goes to creditors. Chapter 13 allows people to save their homes from foreclosure and keep their vehicles.
Bankruptcy filing rising after decline
The number of personal bankruptcies filed annually fell sharply for more than a decade before the recent uptick, hitting a low of about 368,000 in 2022, down from about 1.5 million in 2010.
That number has climbed steadily since 2022.
A 2005 law called the Bankruptcy Abuse Prevention and Consumer Protection Act sparked the earlier decline. Its goal was to make declaring bankruptcy harder and more expensive. Many creditors pushed for these changes because they felt some individuals were abusing the system.
The changes introduced income limits for eligibility to declare Chapter 7 bankruptcy. It also required people to get credit counseling before filing to see whether there was any way they could avoid bankruptcy. It also added a new obligation: Americans now take a course in financial management after they file for bankruptcy to reduce the chance of future money troubles.
One interesting study regarding the legislation’s impact found that it lowered credit card interest rates, but it also prevented some people without health insurance from wiping out their medical debts.
The 2005 changes caused the number of personal bankruptcies to plunge. That ended with the Great Recession, which lasted from late 2007 until mid-2009.
This economic downturn pushed up the number of bankruptcies dramatically. But then the number fell from 2010 until 2022, as the Great Recession’s impact gradually receded. The decline continued into the early 2020s because the stimulus checks and more generous unemployment insurance payments the government provided at the height of the COVID-19 pandemic helped keep millions of U.S. consumers afloat.
The numbers began to rise again in 2022 as American consumers began facing increasing stress from income that has not kept pace with inflation and a sharp jump in credit card interest rates.
Lasting changes
Bankruptcy stays on your credit report for up to 10 years. After that, creditors are supposed to treat people who filed for it like anyone else. A study I worked on with law professor Lois Lupica tracked what happened over two decades to both people who had and had not declared bankruptcy. We wanted to see whether those who had filed for bankruptcy really got out of their financial hole.
Our findings were a good news, bad news story. The good news was that bankruptcy was not causing permanent financial stigma. The average person who declared bankruptcy eventually caught up financially with their peers who hadn’t.
The bad news was that it took 15-25 years to recover in almost all financial dimensions. This is longer than those 10 years that the bankruptcy filing stays on your credit report.
In short, we determined that bankruptcy does give people a fresh start, but getting that reprieve takes longer than the law’s intent.
Strategies that can stave off bankruptcy
My wife and I avoided bankruptcy primarily by doing two things.
First, we switched to using cash for most of our day-to-day purchases. When our wallets were empty, we were done spending. I talk more about this in my 2025 book “The Power of Cash.”
Second, we contacted the financial company where we owed our biggest monthly payment. After providing proof of financial hardship, they were surprisingly flexible.
If these two steps are not enough for you, the next step is to consult an attorney who specializes in bankruptcy law. While there are lots of things most people can competently do on their own, filing for bankruptcy is not one of them.
Jay L. Zagorsky, Associate Professor of Business, Boston University
This article is republished from The Conversation under a Creative Commons license. Read the original article.

financial wellness
Life insurance is on the to-do list. Right under cleaning out the garage.
No matter how you define “adulting,” getting life insurance tends to be one part of the to-do list that keeps getting set on a procrastination loop. New survey data backs that up: there are plenty of other tasks adults would rather focus on first.
(Sheeka Sanahori) Being an adult comes with a never-ending list of responsibilities: Cook dinner. Scrub the bathroom. File taxes. The tasks grow even longer when sharing a household with a partner, building a family, or taking care of others. No matter how you define “adulting,” getting life insurance tends to be one part of the to-do list that keeps getting set on a procrastination loop.
New survey data backs that up: there are plenty of other tasks adults would rather focus on first.
The Adulting Task Americans Keep Avoiding
According to the 2026 Life Happens Life Insurance Survey, a financial literacy nonprofit organization, 39% of U.S. adults would rather clean out their email inbox than figure out their life insurance needs. Another 31% would rather clean out the garage or basement. One in five U.S. adults would be willing to sit on hold with customer service for three hours before life insurance planning. Even though many adults have it somewhere on their list, nearly half (46%) say they’ll either deal with it later or not at all.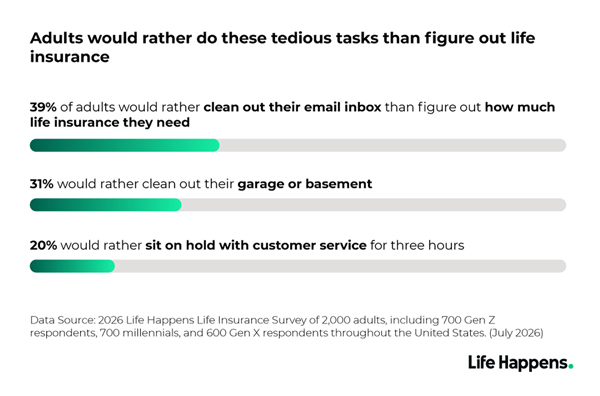
They Know It Matters
Nearly a third of adults have already figured out a life insurance plan, and they feel good about their decision. Others are feeling more conflicted: 14% have a policy, but they’re not sure if they have enough. Another 12% say they either don’t know where to start or they think it’ll be too expensive.
It’s no wonder people are putting it off: Navigating a new-to-them form of financial planning can come with a lot of complicated emotions. Four in 10 feel either overwhelmed, anxious, or some combination of both. Sixteen percent of U.S. adults feel guilty for putting it off, but when the outcome is more procrastination, that feeling lingers.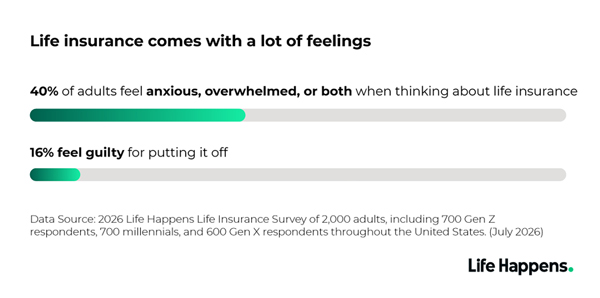
Why Later Keeps Winning
If you’ve ever faced an important decision without having enough information to make an informed choice, you know how stressful it can be. While the generations have different takes on making major decisions with a gut feeling or “pure vibes,” most of the time, people want to feel like they’re making an informed choice. Forty-five percent of U.S. adults say cost concerns, confusion or procrastination are the main reasons they have delayed or would delay looking into life insurance. For more than one in five, the plan is to seriously look at it when they feel more financially stable. For 12%, they say they’ll do it when they’re older.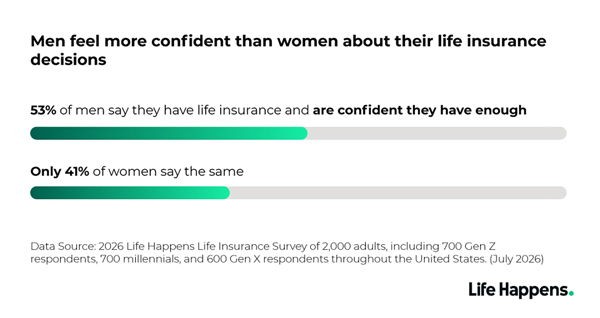
Men tend to feel more confident about their life insurance decisions to date; 53% of men vs. 41% of women feel confident their family would be financially protected.
The First Step Feels Bigger Than It Is
Learning more about life insurance, how it’s priced and how it works could help get many consumers out of their procrastination loop. A quarter of people say they’d make a decision if they learned it was easier to get than they previously thought. Thirty percent would make the purchase if they learned it was more affordable than they believed it to be. Others need an experienced professional to talk to or an online calculator tool to give them guidance.
Methodology: Life Happens commissioned Atomik Research to conduct an online survey of 2,000 adults, including 700 Gen Z respondents, 700 millennials, and 600 Gen X respondents throughout the United States. The margin of error for the overall sample is +/- 2 percentage points and +/- 4 percentage points for each generational sample, with a confidence level of 95 percent. Fieldwork took place between July 14 and July 20, 2026. Atomik Research, part of 4media group, is a creative market research agency.
Photo courtesy of Shutterstock (couple using computer)

SOURCE: