Connect with us

financial wellness

Older adults with dementia misjudge their financial skills – which may make them more vulnerable to fraud, new research finds

Published

on

Last Updated on June 17, 2025 by Daily News Staff

file 20250529 62 4kdk55.jpg?ixlib=rb 4.1
Older adults generally have a good sense of their own financial abilities – unless they have dementia.
shapecharge/E+ via Getty Images

Ian McDonough, Binghamton University, State University of New York

Older adults diagnosed with dementia lose their ability to assess how well they manage their finances, according to a recent study I co-authored in The Gerontologist. In comparison, people of the same age who don’t have dementia are aware of their financial abilities – and this awareness improves over time.

For our study, we used data from over 2,000 adults in the U.S. age 65 and older, collected during a long-term study on aging.
We focused on how participants’ financial skills changed over time. The study began in 1998 and is still running, but we probed data collected between 1998 and 2009.

Participants were assessed at one year, two years, five years and 10 years for their ability to carry out everyday tasks, including ones that required handling money. For example, they had to calculate the cost of a gym membership and a store discount rate, fill out part of a tax return and assess the cost of medical services. They also rated how well they thought they could do everyday financial tasks. Initially, none of the participants were diagnosed with dementia, but over the course of the decade, 87 participants, or 3.1%, received a dementia diagnosis.

We found that even though participants’ performance on financial tasks declined as they aged, older adults who did not have dementia and older adults who had mild cognitive impairment were appropriately aware of their financial abilities. What’s more, that awareness increased over time. However, participants who were diagnosed with dementia during the study and experienced severe cognitive decline often misjudged how well they performed financial tasks.

Financial scams targeting older adults are on the rise.

The lack of insight into one’s cognitive abilities is called anosognosia. This study reveals a new type called financial anosognosia.

Why it matters

As people get older, their financial management skills start to deteriorate. The combination of a lifelong accumulation of wealth, declining financial abilities and a lack of awareness of those declines puts older adults at serious risk for financial scams.

Few tools are available that can support families in helping cognitively impaired adults manage their finances. Our research suggests that there is a critical window of time after people begin to experience cognitive decline during which they are still aware of their financial abilities. We believe that this is when people can take action to secure their finances and develop systems to protect themselves from fraud.

What still isn’t known

Close friends or family members are often tempted to take away the financial autonomy of an older adult who is mismanaging their finances. However, that may not be the best solution, particularly for people who feel that handling their finances is a core part of their identity. More research is needed to identify how best to balance personal autonomy and the need to protect a person’s finances.

What’s next

This study used paper-and-pencil tasks to assess financial performance. But increasingly, many older adults are using online banking.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

E-banking simplifies many calculations, which may be helpful for older adults with declining cognition. However, e-banking can also make finances more of a black box, which may decrease a person’s awareness of their financial abilities. Furthermore, e-banking is constantly advancing, putting older adults at a disadvantage because they are more likely to be less cognitively flexible and to learn more slowly.

We hope to explore whether older adults with and without cognitive decline have similar awareness of their ability to appropriately manage their finances online and identify potential financial scams.

The Research Brief is a short take on interesting academic work.The Conversation

Ian McDonough, Associate Professor of Psychology, Binghamton University, State University of New York

This article is republished from The Conversation under a Creative Commons license. Read the original article.

Continue Reading
Advertisement SodaStream USA, inc

Consumer Corner

5 Hidden Ways to Save on Home Insurance Costs

Lowering Home Insurance Costs? Many home improvements offer an added bonus of unlocking insurance discounts, but these savings opportunities can easily fly under the radar when you aren’t actively on the lookout for them.

Published

on

5 Hidden Ways to Save on Home Insurance Costs

5 Hidden Ways to Save on Home Insurance Costs

(Feature Impact) When you’re planning home improvements, you’re often thinking about improving the comfort, safety, aesthetic or value of your home. Many changes and renovations have the added bonus of unlocking insurance discounts, but these savings opportunities can easily fly under the radar when you aren’t actively on the lookout for them.

“Homeowners tend to think about their insurance when they buy the house or when they have a claim, but a lot can change in between,” said Larry Anderson, director of underwriting operations at Mercury Insurance. “Something as simple as reviewing your policy with your agent once a year can help make sure your coverage still reflects your home today and identify improvements or other factors that may qualify you for additional savings.”

The experts at Mercury Insurance, a multiple-line insurance carrier emphasizing competitive rates and excellent customer service, encourage homeowners to consider these five ways to save on home insurance costs.

Updating Older Parts of the Home

As a home ages, it’s wise to look at what parts and systems may be deteriorating and need upgrades for modernity or safety reasons. Replacing older electrical, plumbing or other major systems can protect your home from emergencies and loss risks. Depending on the state you live in, your specific policy and the improvements you made, it can also qualify your property for an updated-home insurance discount.

Keep records of major improvements – including receipts, work permits and information about when the work was completed – and plan to discuss the upgrades during your next insurance review.

18121 B detail embed1Adding Protective Technology

Beyond replacing the batteries in your smoke detectors, you can outfit your home with a variety of protective devices that make a difference to insurers. Consider options like monitored burglar and fire alarms, smart water sensors and automatic water shutoff systems designed to detect problems before they become major losses. Remember, while security upgrades can make your home less risky to insure, they won’t save you money if your insurer doesn’t know you’ve installed them.

Improving Resilience to Damage

If you live in an area prone to extreme weather or other hazards, resilience upgrades could both safeguard your home and access insurance savings. Depending on your location, qualifying improvements could include a stronger roof, wildfire mitigation measures or flood defense options. Local insurance agents can provide more specific guidance on ways to make your home less vulnerable to damage – or whether you’re eligible for discounts because of work you’ve already completed.

Qualifying for Community Programs

Even if you haven’t personally made renovations to your home, certain changes in your community could help you save on insurance. That could include local wildfire mitigation measures, membership in a qualifying homeowners association or other neighborhood characteristics that affect coverage options, but specific programs vary by location.

Reviewing Insurance Products and Discounts

Whether something significant has changed in your home or community or not, it’s always valuable to review your insurance coverage on a regular basis. For instance, there may be new products or discounts that simply didn’t exist when you originally purchased your policy. Beyond savings considerations alone, ask your agent questions to make sure your coverage still reflects your circumstances and goals.

“Finding savings is always welcome, but the bigger goal of a policy review is making sure your insurance keeps pace with your life and your home,” Anderson said. “A house isn’t static. We improve it, maintain it and protect it in new ways over time. Your insurance should keep up with those changes.”

For more information on homeowner coverage and discount eligibility, visit MercuryInsurance.com.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

Questions to Consider During Your Annual Insurance Checkup

An annual insurance review is an opportunity to look for savings and update coverage. Use these questions as a jumping-off point for discussions with your agent:

  • What has changed about my home?
  • What has changed about my property or community?
  • Have my circumstances changed?
  • Are discounts available today that weren’t when I purchased my policy?
  • Does my coverage still reflect what it would cost to repair or rebuild my home today?

Photos courtesy of Shuttersotck collect?v=1&tid=UA 482330 7&cid=1955551e 1975 5e52 0cdb 8516071094cd&sc=start&t=pageview&dl=http%3A%2F%2Ftrack.familyfeatures track

SOURCE:

Mercury Insurance

📰 Enjoying STM Daily News? Join the conversation!

💬 Leave a comment, share your thoughts, and subscribe to our newsletter for the latest stories, updates, and “News You Can Use This Moment!” delivered to your inbox.

Stay connected with STM Daily News!

Start Your Morning Informed

Get the STM Morning Brief delivered to your inbox every weekday with breaking news, transportation updates, technology, science, and trending stories.

STM News Brief Ad 2

We don’t spam! Read our privacy policy for more info.

Advertisement
Get More From A Face Cleanser And Spa-like Massage
Continue Reading

Health and Life Insurance

Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think

Life is the most valuable thing you have – and like all valuable things, it should be insured. Even thinking about life insurance can be stressful, so it’s one of those things that’s easy to put off and tell yourself you’ll do another day. Consider these four ways to make getting life insurance simpler than you thought.

Published

on

Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think

Lessons in Life Insurance: 4 Reasons Getting It May Be Easier Than You Think

(Feature Impact) Life is the most valuable thing you have – and like all valuable things, it should be insured. Even thinking about life insurance can be stressful, so it’s one of those things that’s easy to put off and tell yourself you’ll do another day.

If that’s how you feel, you aren’t alone. According to the 2026 Life Happens Life Insurance Survey, nearly half (46%) of U.S. adults have getting life insurance on their to-do list but plan to deal with it later or not at all. Confusion, procrastination and cost concerns are among the main reasons people kick this can down the road, according to 45% of respondents.

Yet the survey also uncovered an interesting disconnect: 69% of Americans said they personally know someone who had life insurance or whose family used a life insurance policy, most often a parent or parent figure (33%), but still haven’t made getting coverage a priority.

“Life insurance isn’t unfamiliar to most Americans,” Life Happens Executive Director Brian Steiner said. “The challenge is turning that awareness into action. People may think life insurance is something they can deal with later, but waiting can leave the people they love financially vulnerable. Getting started doesn’t have to be complicated, and professional guidance can help you find protection that fits your needs and budget.”

Consider these four ways to make getting life insurance simpler than you thought.

Watch this video to learn more

https://youtube.com/watch?v=ZaCW8BUQkIs%3Fsi%3DhnRfe5n-67h4VyxQ%26controls%3D0
1. Find a policy that’s a fit.

Roughly 4 in 10 survey respondents reported feeling overwhelmed, anxious or some combination of both about planning for life insurance, with 12% citing thinking it’ll be too expensive as a reason they’ve delayed looking into, buying or updating life insurance.

The good news: There’s a policy that’s right for your current needs. It may be term life insurance, which provides protection for a specific period of time, like to cover a mortgage or tuition for children. There’s also permanent life insurance, which offers lifelong protection, as long as you pay the premiums.

2. Take advantage of digital tools

One-quarter of respondents said they’d be more likely to look into life insurance if they learned it was easier to get than they thought, and digital tools can help make that demand a reality.

It can take as little as two minutes to find out how much you need, for example, with the life insurance needs calculator from the nonprofit Life Happens. Just answer a few simple questions to estimate the amount of life insurance coverage you may need to take care of your family.

3. It’s about protection, not perfection.

Part of the anxiety around life insurance may be the perception that it should be perfect. For more than 1 in 5 survey participants, the plan is to seriously look at it when they feel more financially stable, and another 12% simply said they’ll do it when they’re older.

However, life insurance doesn’t have to check all the boxes for every stage of your life – you can find what works for your family right now then adjust as things change over time.

Advertisement
Get More From A Face Cleanser And Spa-like Massage
4. Professional help is available.

Perhaps the biggest hurdle to tackling life insurance is the feeling that you’re in it alone. Overall, 55% of respondents said if they learned life insurance may be easier to get than they expected, they’d be more likely to start the process.

With professional help only a few clicks away, you can rest assured you’re on the path to a life insurance fit that’s right for you by visiting findapro.lifehappens.org.

Photo courtesy of Shutterstock collect?v=1&tid=UA 482330 7&cid=1955551e 1975 5e52 0cdb 8516071094cd&sc=start&t=pageview&dl=http%3A%2F%2Ftrack.familyfeatures track

SOURCE:

Life Happens

Continue Reading

Economy

Bridging the Gap Between Military Experience and Civilian Careers: 5 Tips for Veterans

Published

on

Bridging the Gap Between Military Experience and Civilian Careers: 5 Tips for Veterans

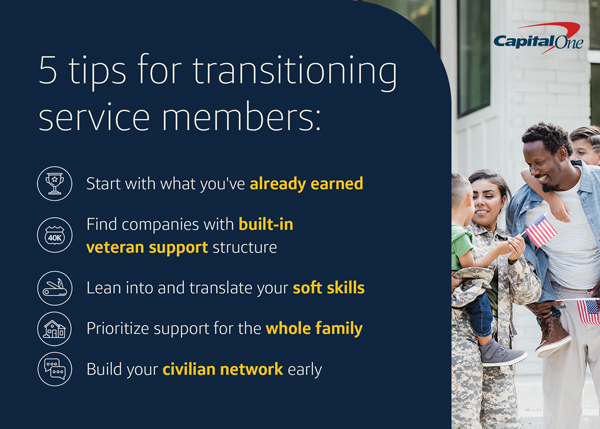
(Feature Impact) Every year, approximately 200,000 service men and women transition from military life to corporate America. Finding the right civilian career is a transition, but it’s an opportunity to leverage military leadership and mission-driven talent.

Traditional hiring processes often focus on conventional resumes, but forward-thinking organizations recognize military experience as a competitive advantage in today’s workforce. The resilience, integrity and adaptability of America’s veterans and military families make them uniquely positioned to drive growth and innovation in their communities.

“Veterans bring unmatched discipline, adaptability and a results-driven mindset that directly translates to high-impact corporate careers,” said Drew Matheson, senior director at Capital One’s Commercial Bank and retired U.S. Army infantry officer. “While military experience doesn’t always fit perfectly on a traditional paper resume, employers like Capital One who know how to decode these unique leadership skills are able to unlock an incredible pipeline of proven performers.”

To help transitioning service members successfully navigate this career pivot, military community leaders at Capital One offer these five essential tips for service members entering the civilian workforce:18007 B detail embed2

Start With What You’ve Already Earned

Opportunity starts with preparation. Beyond the well-known Post-9/11 GI Bill, which can cover tuition, housing and books, transitioning service members can look into vocational rehab or the SkillBridge program, which allows them to do civilian internships during the last 180 days of service. Many employers also offer internal tuition reimbursement programs. Taking the time to proactively map out these benefits ensures you aren’t leaving valuable opportunities or money on the table.

Find Employers with Veteran Support Structures

With almost half of veterans leaving their first post-military job within a year, according to research published by the Institute for Veterans and Military Families and VetAdvisor, finding the right culture and community is key to a successful transition. Look for employers with active veteran networks and dedicated mentorship.

For example, Capital One’s Salute Business Resource Group serves as a thriving internal community of more than 6,000 members, offering peer support, year-round professional development and mentorship for veterans, reservists and military spouses. Additionally, partner organizations like Hiring Our Heroes provide career workshops, fellowships and job fairs to ensure you’re employment-ready from day one.

Lean Into and Translate Your Soft Skills

Veterans bring a distinct competitive advantage to the applicant pool. You should confidently lean into the cross-functional “soft skills” learned in the line of duty such as risk management, crisis resolution and building trust under high-pressure scenarios.

The trick is translating these capabilities out of military jargon on your resume. Swap military terms like “NCOIC” for “Operations Manager” or “commanded” for “directed.” To make this easier, look for military-friendly employers that employ dedicated military recruiters who specialize in decoding military resumes to align skills with the right roles.

Prioritize Support for the Whole Family

Military service is a family commitment, and the transition out of uniform affects everyone. Military spouses often face unique career hurdles, including frequent relocations and employment gaps. When evaluating employers, look for companies that offer holistic benefits and flexible structures.

For example, Capital One, recognized by “U.S. Veterans Magazine” as a Top Veteran Employer and Top Military Spouse Employer, actively supports military spouses and families through dedicated spouse hiring initiatives and internal support mechanisms. Furthermore, look for organizations that support continued military training and active-duty leave, ensuring military associates never have to choose between their service and their careers.

Build Your Civilian Network Early

In the military, your network is built in. In the civilian world, you have to cultivate it. Long before your terminal leave begins, connect with veterans who work at companies you admire. Reach out for brief, 15-minute informational interviews to learn about their transition journeys rather than simply asking for a job. With more than 70% of civilian jobs filled through networking, according to estimates from Career Horizons, making organic connections early is a powerful tool for getting your foot in the door.

Advertisement
Get More From A Face Cleanser And Spa-like Massage

To find additional resources and learn more about how to support the hiring of veterans and military spouses, visit CapitalOneCareers.com/Military.

Photo courtesy of Shutterstock collect?v=1&tid=UA 482330 7&cid=1955551e 1975 5e52 0cdb 8516071094cd&sc=start&t=pageview&dl=http%3A%2F%2Ftrack.familyfeatures track

SOURCE:

Capital One

Continue Reading

Trending