Lifestyle
Self-forgiveness is more than self-comfort − a philosopher explains
Self-forgiveness requires confronting negative emotions, acknowledging wrongdoing, and is essential for moral growth and healthier relationships.

Last Updated on March 7, 2026 by Daily News Staff

Mordechai Gordon, Quinnipiac University
As the Jewish High Holidays approach, which begin with Rosh Hashanah and continue with Yom Kippur, the theme of forgiveness keeps coming to my mind.
The 10 days from Rosh Hashanah to Yom Kippur are referred to in the Jewish tradition as the days of repentance, or the days of awe. During this period, Jews who observe the holidays implore God to respond to their sins with mercy, while also requesting forgiveness from anyone those individuals may have wronged in the past year.
Most conversations about forgiveness focus on the meaning and value of forgiving others. Douglas Stewart, a philosopher of education who has researched forgiveness extensively, writes that to forgive implies a willingness to let go of our negative emotions or hard feelings and to adopt in their place a more generous and compassionate attitude toward our wrongdoers.
Other philosophers have pointed out that the benefits of forgiveness include overcoming resentment, restoring relationships and setting a wrong to rest in the past – without vengeance. As such, to forgive should be considered morally valuable and admirable.
But what about self-forgiveness? Is it morally valuable, or just something we do to make ourselves feel better? And what is self-forgiveness, anyway?
As a philosopher of education, some of my own research has wrestled with these questions.

Defining self-forgiveness
Self-forgiveness means managing to work through painful feelings such as guilt, shame and deep disappointment with ourselves. It entails transforming negative attitudes, such as contempt, anger and shame, into more positive emotions such as respect and humility.
It is important to recognize, however, that a wrongdoer cannot simply reject shame: They must confront it. Moral philosophers such as Byron Williston assert that people who have deeply wronged others, such as betraying a loved one, need to experience shame and take responsibility for their actions – such as asking for forgiveness. Otherwise, an attempt at self-forgiveness is not likely to be meaningful.
Finally, we need to keep in mind that self-forgiveness does not imply someone has extinguished all the negative feelings directed at themselves or is done with self-reproach. This would amount to an impossible goal.
Rather, as philosopher Robin Dillon pointed out, self-forgiveness suggests that someone is no longer being consumed or overwhelmed by those negative feelings. In short, it is possible to forgive ourselves and still view ourselves with a demanding and critical eye.
Moral development
Getting there, though, is not easy. Self-forgiveness entails working through a rigorous process of coming to terms with wrongdoing.
According to ethicist Margaret Holmgren, that process includes at least four steps: acknowledging that what we did was wrong; coming to terms with why it was wrong; allowing ourselves to experience grief and self-resentment at having injured another person; and, finally, making a genuine effort to correct the attitudes that led to the harmful act and making amends to the victim.
In other words, confronting negative emotions, attitudes and patterns is essential prior to attempting to restore relationships with others. Only once we are able to relax the preoccupation with guilt and shame, and to genuinely forgive ourselves, can we meaningfully contribute to relationships as liberated and equal partners – especially in ongoing ones, such as with family and friends.
Of course, there are cases in which the offense is so vast, such as genocide, that no individual can make full restitution or provide an adequate apology for the wrong.
There are other times when an apology is impossible. Perhaps victims are dead; perhaps a direct apology would retraumatize them or do more harm than good.
In those cases, I would argue, an offender can still attempt to work toward self-forgiveness – acknowledging not only the victim’s intrinsic worth but their own, regardless of their ability to make amends. This in itself is moral growth: appreciating that neither is a mere object that can be manipulated or abused.
The take-home point, I would argue, is that going through the process of self-forgiveness is morally beneficial. It can not only liberate people who tend to reproach themselves incessantly, but it can enhance their ability to relate ethically toward others – to acknowledge wrongdoing, while simultaneously affirming their own value.
Most people have experienced at least one situation in which they inflicted pain on someone else and recognized that their words or actions caused harm. In such situations, we also often feel ashamed of ourselves and attempt to apologize or make amends.
Yet I hope that during this High Holiday season we keep in mind that self-forgiveness should also be considered essential. If moral development means a process in which our self-awareness and character mature, then acknowledging wrongdoing and experiencing shame, followed by self-forgiveness, are indispensable for that process.
Mordechai Gordon, Professor of Education, Quinnipiac University
This article is republished from The Conversation under a Creative Commons license. Read the original article.
Our Lifestyle section on STM Daily News is a hub of inspiration and practical information, offering a range of articles that touch on various aspects of daily life. From tips on family finances to guides for maintaining health and wellness, we strive to empower our readers with knowledge and resources to enhance their lifestyles. Whether you’re seeking outdoor activity ideas, fashion trends, or travel recommendations, our lifestyle section has got you covered. Visit us today at https://stmdailynews.com/category/lifestyle/ and embark on a journey of discovery and self-improvement.

Community
4 Ways to Preserve Veterans’ Stories for Future Generations
Family stories, photographs, letters and memories all have a place in the broader story of humanity, but if they aren’t recorded and preserved, they can fade over time. Consider these ways to help the veterans in your life preserve their stories and leave their mark on history. Preserve Veterans’ Stories for Future Generations

4 Ways to Preserve Veterans’ Stories for Future Generations
(Feature Impact) History is built from stories and memories, which is why it’s important to listen to the people who were there as the world changed. Family stories, photographs, letters and memories all have a place in the broader story of humanity, but if they aren’t recorded and preserved, they can fade over time.
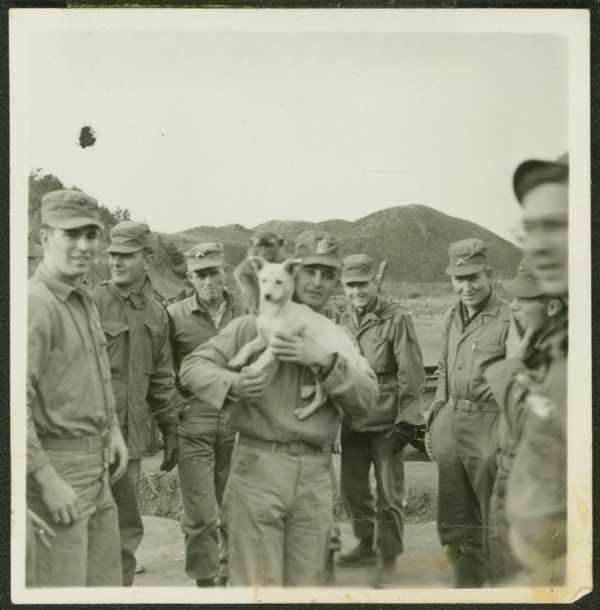
Because more than 70 years have passed since the Korean War ended, opportunities to hear firsthand accounts from earlier conflicts grow fewer as time passes. Veterans and their families may be able to help record stories and lessons from “The Forgotten War” that might otherwise be lost.
You don’t need to be a historian to help preserve your loved ones’ memories and experiences. Programs like the Library of Congress Veterans History Project are dedicated to collecting stories from people like Private First Class Robert Lawrence Barber, who wrote regular letters home to his mother while serving in Korea. They paint a harrowing picture of combat, exhaustion, cold, fatigue and the stark realities of war that should never be forgotten. Experiences away from combat can be equally revealing, from daily routines and friendships to unexpected challenges.
Consider these ways to help the veterans in your life preserve their stories and leave their mark on history.
Start the Conversation Now
When it comes to recording memories, time is of the essence, especially for those who served in Korea. Decades may have passed, but each day makes a difference. Sit down with your loved one and gently start the conversation. You don’t have to get the entire backstory at once, but you can begin asking questions about their military experience and give them time to gather their thoughts.
 Record Their Story
How a story is told can add dimension to the story itself. An audio or video recording preserves your loved one’s voice, expressions and emotions along with their words, giving your family memories to look back on for generations. Choose a quiet, comfortable space and test the equipment before recording.
Consider Preserving the Story Beyond Your Family
Family stories are most meaningful to those who know and love the storyteller, but they also matter to the world. Sharing veterans’ stories – including difficulties and ordinary moments – offers others a firsthand view of military life. Libraries and oral history archives may be able to preserve qualifying material for a wider audience.
“We want all stories, not just those from the foxhole or the battlefronts, but from all veterans who served the United States in uniform,” said Monica Mohindra, director of the Veterans History Project. “What did they hear? What did they see? What did it mean to them?”
If you have oral history interviews, and/or original photographs, letters or other records, consider contributing them to be archived and made accessible to future generations. Staff members are available to help you curate and select physical materials to contribute to the nation’s library.
Give Old Photos and Letters Context
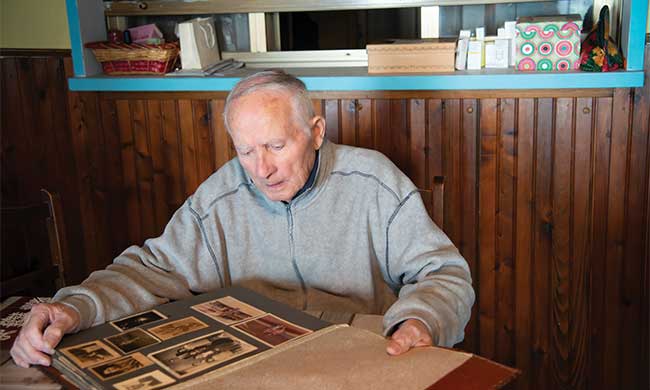
Brush the dust off those old photo albums, scrapbooks and memory boxes because they may contain tangible pieces of history. A photograph, letter or piece of memorabilia could be what a veteran needs to bring fuzzy memories back into focus – whether it’s seeing the face of an old comrade or reading a letter written home. That gives you the opportunity to hear new stories and fill in context.
Learn more, discover veterans’ histories and find instructions for contributing veterans’ stories at loc.gov/vets.
Photo courtesy of Shutterstock (man looking at photo album)
Photo courtesy of the Library of Congress (group of soldiers)
SOURCE:
Library of Congress Veterans History Project

Lifestyle
Beyond the Piggy Bank: How to Build Your Child’s Financial Future
Your Child’s Financial Future: When money is tight, saving for the future can feel out of reach. Rent, groceries and bills come first, but building something for your kids doesn’t have to start with your paycheck. For millions of families, there’s already money waiting.
Beyond the Piggy Bank: How to Build Your Child’s Financial Future
(Feature Impact) When money is tight, saving for the future can feel out of reach. Rent, groceries and bills come first, but building something for your kids doesn’t have to start with your paycheck. For millions of families, there’s already money waiting.
Michael and Susan Dell put $250 into the 530A (Trump) Accounts of 25 million children across the United States. Children born between 2016-2024 who live in eligible ZIP codes received the money. Families didn’t have to apply, and they don’t have to pay anything back.
“Every American child now has their own investment account,” said Matt Lira, executive director at Invest America, a nonprofit that helps families understand investing. “It’s in your child’s name, it’s built to grow and it’s theirs from the very start. That’s a real stake in America’s future. Claiming it takes a few minutes, and your child begins life as an owner.”
U.S. children under 18 with valid Social Security numbers already have accounts in their names, and any money in it is invested so it can grow over time. You just need to claim it. Download the official app, available on iOS or Android, or go to the official website then sign in as a parent or guardian to access your child’s account. You can choose to add money if you want, but it’s not required. Claiming the account also lets friends, family, employers and others contribute.
“Parents and grandparents, please claim your child’s account,” said Susan Dell, co-founder of the Michael & Susan Dell Foundation. “These accounts are ready. They’re waiting for you, and they have money in them. Claim your child’s account and start adding money to their account and preparing a wonderful future for them.”
Money Lessons That Don’t Cost a Thing
Claiming the account is the first step. Helping your child understand it is the next. When kids know they own something that can grow, money lessons stop feeling abstract. These everyday habits can help them make the most of it:
- Let them see how you make choices. You probably already compare prices, stretch a grocery budget and decide what can wait. Talk through those choices out loud. When kids hear why you picked the store brand or skipped something this week, they can learn how to tell needs from wants.
- Give them a little to manage. Birthday money, a few dollars for chores or earnings from mowing lawns or babysitting are all chances to practice. Let kids decide how much to spend and how much to save then talk about how it went.
- Explain saving vs. investing. Saving is putting money aside for something you want soon, like a bike. Investing is letting money grow over many years. For example, 530A (Trump) Accounts are a real-life example of investing that kids can check a few times a month to see how money grows.
- Talk about what they dream of.Ask your kids what they want someday, like a car, college, a trade, their own business or a home. Knowing they have money saved or invested can help them dream bigger, because those goals start to feel possible instead of out of reach.
Small Amounts Still Count
If you’re ever able to add something to an investment account, even a few dollars now and then, it has years to grow. Relatives can help, too. A small amount on a birthday or holiday adds up over a childhood. However, if adding money isn’t possible right now, that’s OK.
“In America, small beginnings can become extraordinary things,” Michael Dell said. “When we invest in children’s futures, we invest in America’s future. We are so excited to see what they build.”
Claim your child’s account today through the official app or at TrumpAccounts.gov.
Common Questions About 530A (Trump) Accounts
What is a 530A (Trump) Account?
It’s a free investment account for U.S. children under 18 powered by the U.S. Treasury. It’s in your child’s name. The money in the account is invested in hundreds of America’s biggest companies at once, so it has the chance to grow over time without you having to pick anything. The account also has tax benefits. The money can grow for years without being taxed along the way, which helps it grow faster.
Does my child have one?
U.S. children under 18 with valid Social Security numbers were signed up automatically, and nearly 70 million children already have accounts. You just need to claim your child’s account to track its value over time and help it grow. You just need to claim your child’s account to track its value over time and help it grow.
How do I claim it?
Download the official app on your smartphone or visit the official website. You’ll confirm some information and claim the account. It only takes a few minutes, and it’s free.
Do I have to put money in?
No. Adding money is always possible, but claiming an account allows other people to contribute, even if you don’t.
Can other people add money?
Yes. Parents, grandparents, other family members, friends and even employers can add money. The total limit is $5,000 per child per year. Other government or charity programs may add money in the future, too.
How were children chosen for the $250 from Michael and Susan Dell?
Families did not apply, and children were not picked one by one. The foundation started with the lowest-income ZIP codes, based on U.S. Census data, and kept adding ZIP codes until it reached 25 million children. Learn more about eligibility at investamerica.org/dell.
My ZIP code wasn’t included. Does my child still have an account?
All U.S. children with a Social Security number have an account. The ZIP codes only decided who got the extra $250.
When can my child use the money?
At 18, your child can decide what to do with it. They can keep it growing for retirement or use it for things like school or buying a first home.
Photos courtesy of Shutterstock
SOURCE:
Michael and Susan Dell Foundation
small business
Navigating the American Dream: How Integrated Financial Tools, Credit and Rewards Can Help Small Businesses Succeed
Last Updated on November 9, 2026 by Daily News Staff
(Feature Impact) Owning a small business has been a cornerstone of the “American Dream” for generations. It represents the chance to transform a passion into a livelihood and legacy. However, turning dreams into reality is rarely a smooth or easy process and requires more than ambition alone. Today’s business owners need support and access to tools that enable them to overcome challenges and keep growing.
Recent research conducted by the Capital One Insights Center shows 75% of more than 1,000 surveyed small business owners with more than one employee and annual revenues of up to $20 million are confident about the future, and 69% believe their business is actively primed for growth.
While this optimism is promising, 47% of business owners still said their operations either stayed the same or became less efficient over the past year, citing issues like back-office friction and fragmented financial systems that make it difficult to get a clear picture of the health of their businesses.
If you’re a small business owner eager to grow but not sure how to get there, start with this advice from real small business owners and experts at Capital One.
//www.youtube.com/embed/VX48mqEaSnE
Identify Sources of Friction
Before you can pour effort into growth, you must understand what barriers are holding you back. Take time to look under the hood of your business to identify where time and energy is being lost.
For example, you may be among the 78% of small business owners who feel stressed and uncertain about expense management – think hours spent hunting for receipts, manually entering numbers into software and reconciling accounts. Operational challenges aren’t just a hassle; they also pull attention away from important priorities like serving your customers and planning for growth.
“We were focused on making as many candles as possible, especially during the busy season,” said Katie Roering, co-owner of Fontana Candle Co. “A lot of the back-office tasks like procurement, raw material purchasing, forecasting – all the really important things – were done at 3 a.m., 8 p.m. or on Saturday and Sunday, and there really just was not enough time in the day to get everything done that we needed to. We just knew as we continued to grow, we needed to streamline our processes, build out our team and keep moving forward.”
 Use Integrated Tools to Manage Finances
Instead of balancing 10 different tracking and analysis tools, you can turn to one-stop solutions to improve efficiency. Time gets lost when you’re forced to manually gather and interpret relevant data before you’re able to act. You need a platform that handles the busywork for you.
Integrated, or “all-in-one,” financial tools – like accounting and bookkeeping platforms with automation capabilities or business credit cards featuring built-in analytical tools – allow you to easily stay on top of cash flow and day-to-day operations. For small businesses where every hour and dollar makes a difference, consolidating and automating systems can have an immediate impact. In fact, 51% of survey respondents said integrated tools have already fueled their growth.
Leverage Credit Access and Rewards Wisely
Growth requires capital, so access to credit is a game-changer for many business owners, with 77% describing it as a key factor in achieving business resilience. Having funds accessible when you need them makes your business more capable of weathering storms such as equipment failures and seasonal slowdowns. It also puts the power in your hands to act when an exciting opportunity presents itself, like an inventory flash sale or the chance to advertise in a new market.
Access to credit comes with another advantage: rewards. By using credit cards for your daily business expenses, you can earn cash back, points or travel rewards. Whether you redeem these to cover everyday expenses, book business trips or reinvest in the business, they can act as a bonus source of income. Learn to maximize rewards like the 84% of small business cardholders surveyed so you aren’t leaving money on the table.
To learn more about how small business owners can identify obstacles, employ integrated financial tools and use credit as a tool for growth, read the full report at capitalone.com/about/insights-center.
Photos courtesy of Shutterstock
SOURCE: