Consumer Corner
What’s in the price of a gallon of gas?

Robert I. Harris, Georgia Institute of Technology
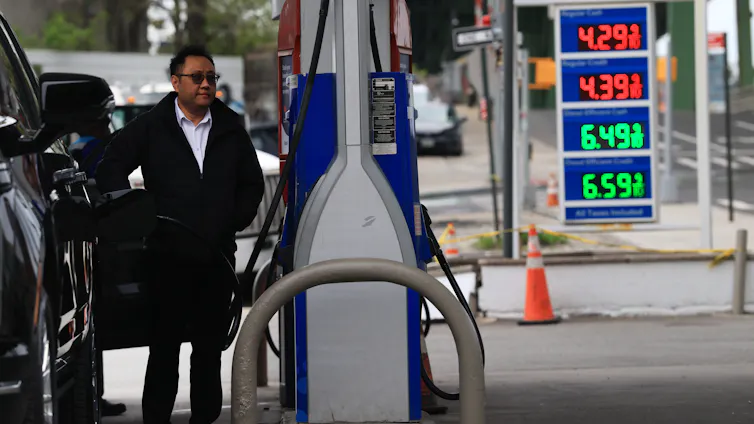
The U.S. Energy Information Administration expects nationwide retail gasoline prices to average near US$4.30 a gallon for April 2026 – the highest monthly average of the year. The political response has been familiar. Georgia has suspended its state gas tax, other states are weighing their own tax holidays, and the White House has issued a temporary waiver of a law known as the Jones Act in hopes of moving more domestic fuel to East Coast ports.
As an energy economist, I am often asked about what contributes to gas prices and what different policies can do to affect them.
The price of a retail gallon of gas is the sum of four things: the cost of crude oil, refining, distribution and marketing, and taxes.
In nationwide figures from January 2026, crude oil accounted for about 51% of the pump price, refining roughly 20%, distribution and marketing about 11% and taxes about 18%. That mix shifts with conditions: When crude oil prices spike, that can drive more than 60% of the price; when the price drops, taxes and logistics are larger shares of the cost.
Crude oil is the biggest ingredient
Because the price of crude oil is the largest element, most of the price at the pump is derived from the global oil market.
Usually, big swings in crude prices come mainly from shifts in global demand and expectations – not from supply disruptions, according to widely cited research in 2009 by the economist Lutz Kilian.
But what is happening in early 2026 with the war in Iran is one of the exceptions: a classic supply shock. Severe disruptions to shipping through the Strait of Hormuz and attacks on Middle East oil infrastructure have taken millions of barrels a day off the global market.
Most drivers generally can’t quickly reduce how much they drive or how much gas they use when prices rise, so gasoline demand doesn’t change much in the short run. That means a jump in crude costs tends to result in people paying more rather than driving less.
Refining, regulations and the California puzzle
Refining turns crude into gasoline at industrial scale. The U.S. doesn’t have a single gasoline market, though. Roughly a quarter of U.S. gasoline is a cleaner-burning blend of petroleum-derived chemicals called “reformulated gasoline,” which is required in urban areas across 17 states and the District of Columbia to reduce smog.
California uses an even stricter formulation that few out-of-state refineries make. California is also geographically isolated: No pipelines bring gasoline in from other U.S. refining regions.
California’s gasoline prices have long run above the national average, explained in part by higher state taxes and stricter environmental rules. But since a refinery fire in Torrance, California, in 2015 reduced production capacity, the state’s prices have been about 20 to 30 cents a gallon higher than what those factors would indicate.
Energy economist and University of California, Berkeley, professor Severin Borenstein has called this the “mystery gasoline surcharge” and attributes it to the fact that there isn’t as much competition between refineries or gas stations in California as in other states. California’s own Division of Petroleum Market Oversight says the surcharge cost the state’s drivers about $59 billion from 2015 to 2024. It’s not exactly clear who is getting that money, but it could be gas stations themselves or refineries, through complex contracts with gas stations.
Getting the gas into your car
The distribution and marketing category covers the costs of everything involved in getting the gasoline from the refinery gate to your tank.
Gasoline moves by pipeline, ship, rail and truck to wholesale terminals, and then by local delivery truck to service stations.
At the retailer’s end, the key factors are station rent and labor, the cost to buy gasoline in bulk to be able to sell it, credit card fees of as much as 6 to 10 cents a gallon at current prices, and franchise fees paid to the national brand, such as Sunoco or ExxonMobil, for permission to put their branding on the gas station.
Most gas station operators net only a few cents per gallon on fuel itself – which is why many gas stations are really convenience stores with pumps out front. Borenstein and some of his collaborators have also documented that retail gas prices rise quickly when wholesale costs climb but fall slowly when wholesale costs drop.
The question of gas tax holidays
The federal government charges a tax on fuel, of 18.4 cents a gallon for gasoline and 24.3 cents a gallon for diesel. States charge their own taxes, ranging from 70.9 cents a gallon for gas in California to 8.95 cents in Alaska.
When gas prices rise, many politicians start talking about temporarily suspending their state’s gas tax. That does reduce prices, but not as much as politicians – or consumers – might hope. Research on past gas tax holidays has found that consumers get about 79% of the reduction in gas taxes. That means oil companies and fuel retailers keep about one-fifth of the tax cut for themselves rather than passing that savings to the public.
Gas tax holidays also reduce funding for what the taxes are designed to pay for, typically roads and bridges. That pushes road and bridge upkeep costs onto future drivers and general taxpayers.
There is an additional problem, too: Taxes on gasoline are supposed to charge drivers for some of the costs their driving imposes on everyone else – carbon emissions, local air pollution, congestion and crashes. But Borenstein has found that U.S. fuel tax levels are already far below the true cost to society. Removing the tax on drivers effectively raises the costs for everyone else.
The Jones Act: A small number that adds up
The 1920 Jones Act is a federal law that requires cargo moving between U.S. ports to travel on vessels built and registered in the U.S., owned by U.S. citizens, and crewed primarily by U.S. citizens and permanent residents. Of the world’s 7,500 oil tankers, only 54 meet this requirement. Only 43 of these can transport refined fuels such as gasoline.
So, despite significant refining capacity on the Gulf Coast, some U.S. gasoline is exported overseas even as the Northeast imports fuel, in part reflecting the relatively high cost of moving fuel between U.S. ports.
Economists Ryan Kellogg and Rich Sweeney estimate that the law raises East Coast gasoline prices by about a penny and a half per gallon on average, costing drivers roughly $770 million a year. In light of the war’s effect on gas prices, the Trump administration has temporarily suspended the Jones Act requirements – an action more commonly taken when hurricanes knock out Gulf Coast refineries and pipeline networks.
What moves the number
The result of all these factors is that the price that drivers see at the pump mostly reflects the global price of crude, plus a stack of domestic costs, only some of which are inefficient.
Tax holidays give a partial, short-lived rebate. Jones Act waivers trim pennies, though permanent repeal may cause more fundamental changes, such as reduced rail and truck transport of all goods, which could lower costs, emissions and infrastructure damage associated with cargo transportation. Harmonizing fuel blends across states and seasons may lower prices somewhat, but likely at the expense of increased emissions.
Ultimately, the best protection against oil price shocks is a more efficient gas-burning vehicle, or one that doesn’t burn gasoline at all. In the meantime, the best I can offer as an economist is clarity about what that $4.30 actually buys.
Robert I. Harris, Assistant Professor of Economics, Georgia Institute of Technology
This article is republished from The Conversation under a Creative Commons license. Read the original article.
📰 Enjoying STM Daily News? Join the conversation!
💬 Leave a comment, share your thoughts, and subscribe to our newsletter for the latest stories, updates, and “News You Can Use This Moment!” delivered to your inbox.
Stay connected with STM Daily News!


Consumer Corner
Cold cities are the most ready for winter, with one exception. See where your city ranks
Cold cities? Every neighborhood has a mix of homeowners who approach seasonal home maintenance differently – there are the people who stay on schedule, and on the other end, the procrastinators. There are the dedicated DIYers, and those who have their favorite maintenance pro saved as a favorite contact in their phone. As it turns out, cities are no different. Some metropolitan areas keep their neighborhoods in tip-top shape, while others are a little more slow-going.

Cold cities are the most ready for winter, with one exception. See where your city ranks
(Sheeka Sanahori) Every neighborhood has a mix of homeowners who approach seasonal home maintenance differently – there are the people who stay on schedule, and on the other end, the procrastinators. There are the dedicated DIYers, and those who have their favorite maintenance pro saved as a favorite contact in their phone. As it turns out, cities are no different. Some metropolitan areas keep their neighborhoods in tip-top shape, while others are a little more slow-going.
New data from home services company Angi, covering fall maintenance activity in August, reveals which U.S. metropolitan areas are the most proactive with fall maintenance. Washington, D.C., tops the ranking with the strongest demand for fall maintenance in the country, followed by Columbus, Ohio, and Milwaukee, Wisconsin. Northern cities dominate the rest of the list.
Cleveland, Ohio, and Albany-Schenectady-Troy, New York, round out the top five. Cold-weather markets dominate the ranking, accounting for eight of the 10 most-prepared metros. Rochester, New York; Charlotte, North Carolina; Chicago; Indianapolis; and Pittsburgh complete the top 10.
Least fall-ready metros
Fewer than 1 in 5 American cities is prepping for fall at an above-average rate. Among the 66 metros that recorded at least 100 fall maintenance service requests during the analysis period, Los Angeles had the lowest level of per-capita activity, followed by Oklahoma City and Riverside, California. California accounts for four of the bottom 10 markets, with Los Angeles, Riverside, San Diego and San Francisco all appearing on the list. These metros historically don’t experience the colder winter climates of the Northeast and Midwest, making fall maintenance less of an imperative.
Grand Rapids, Michigan, stands out as the only clearly cold-weather metro among the 10 least-prepared large metros. The New York City metro, which includes Newark and Jersey City, ranked just outside the 10 least-prepared large metros, coming in at number 11. Other New York state metros, including Syracuse, Rochester and the Albany metro area, were on the most prepared list.
Homeowners are choosing upkeep over upgrades
Sixty-three percent of homeowners who have recently hired a professional completed maintenance work, and 58% completed repairs. Although they may be waiting to do that dream kitchen or bath renovation, they’re focusing for now on the maintenance that keeps their homes in order.
The most common fall maintenance projects focus on outdoor upkeep. Nationally, tree trimming was the most popular, followed by lawn and yard waste cleanup and shrub care.
What homeowners should do now
When tackling a home maintenance list, start at the top of the home by inspecting the roof and gutters. Look for loose or damaged shingles, and make sure gutters are debris-free. It’s also a good idea to ensure downspouts direct water far away from the foundation. Homeowners should inspect these areas from the ground or hire a professional if the work requires climbing or feels unsafe.
Next, check for drafts around the windows and doors. Replacing worn weatherstripping and damaged caulk in the fall can prevent warm air from escaping once the heat comes back on. Homeowners should also inspect their HVAC filters and have the heating system checked before the temperatures drop.
Every home’s maintenance needs will vary, depending on the age and condition of the house and where it’s located. Whether homeowners hire a professional or safely address small issues, making the fixes can prevent larger and more expensive problems later.
The ranking: Metros from most to least prepared
America’s 10 Most Fall-Prepared Metros
1. Washington, D.C.
2. Columbus, Ohio
3. Milwaukee, Wisconsin
4. Cleveland, Ohio
5. Albany-Schenectady-Troy, New York
6. Rochester, New York
7. Charlotte, North Carolina
8. Chicago, Illinois
9. Indianapolis, Indiana
10. Pittsburgh, Pennsylvania
10 Metros With the Most Opportunity to Get Fall-Ready
1. Los Angeles, California
2. Oklahoma City, Oklahoma
3. Riverside, California
4. Miami, Florida
5. San Diego, California
6. Houston, Texas
7. Grand Rapids, Michigan
8. San Francisco, California
9. Austin, Texas
10. Memphis, Tennessee
Methodology
The rankings are based on fall maintenance activity recorded on Angi during August 2026. Projects included yard cleanup, winterization, roofing and gutters, heating systems, water and drainage, outdoor plumbing, fireplaces and chimneys, pest prevention, and snow and storm preparation. U.S. metropolitan areas were ranked by activity per 100,000 residents using 2020 U.S. Census population data. To qualify for the least-prepared ranking, metros were required to have at least five service requests or jobs during the analysis period. The rankings reflect activity on Angi’s platform and are not a complete measure of all home-maintenance activity within each metro. These rankings reflect activity observed on Angi’s platform and should not be interpreted as a complete measure of all home-maintenance behavior within a metro area.
Photo courtesy of Shutterstock
SOURCE:
Angi

Consumer Corner
5 Hidden Ways to Save on Home Insurance Costs
Lowering Home Insurance Costs? Many home improvements offer an added bonus of unlocking insurance discounts, but these savings opportunities can easily fly under the radar when you aren’t actively on the lookout for them.
5 Hidden Ways to Save on Home Insurance Costs
(Feature Impact) When you’re planning home improvements, you’re often thinking about improving the comfort, safety, aesthetic or value of your home. Many changes and renovations have the added bonus of unlocking insurance discounts, but these savings opportunities can easily fly under the radar when you aren’t actively on the lookout for them.
“Homeowners tend to think about their insurance when they buy the house or when they have a claim, but a lot can change in between,” said Larry Anderson, director of underwriting operations at Mercury Insurance. “Something as simple as reviewing your policy with your agent once a year can help make sure your coverage still reflects your home today and identify improvements or other factors that may qualify you for additional savings.”
The experts at Mercury Insurance, a multiple-line insurance carrier emphasizing competitive rates and excellent customer service, encourage homeowners to consider these five ways to save on home insurance costs.
Updating Older Parts of the Home
As a home ages, it’s wise to look at what parts and systems may be deteriorating and need upgrades for modernity or safety reasons. Replacing older electrical, plumbing or other major systems can protect your home from emergencies and loss risks. Depending on the state you live in, your specific policy and the improvements you made, it can also qualify your property for an updated-home insurance discount.
Keep records of major improvements – including receipts, work permits and information about when the work was completed – and plan to discuss the upgrades during your next insurance review.
 Adding Protective Technology
Beyond replacing the batteries in your smoke detectors, you can outfit your home with a variety of protective devices that make a difference to insurers. Consider options like monitored burglar and fire alarms, smart water sensors and automatic water shutoff systems designed to detect problems before they become major losses. Remember, while security upgrades can make your home less risky to insure, they won’t save you money if your insurer doesn’t know you’ve installed them.
Improving Resilience to Damage
If you live in an area prone to extreme weather or other hazards, resilience upgrades could both safeguard your home and access insurance savings. Depending on your location, qualifying improvements could include a stronger roof, wildfire mitigation measures or flood defense options. Local insurance agents can provide more specific guidance on ways to make your home less vulnerable to damage – or whether you’re eligible for discounts because of work you’ve already completed.
Qualifying for Community Programs
Even if you haven’t personally made renovations to your home, certain changes in your community could help you save on insurance. That could include local wildfire mitigation measures, membership in a qualifying homeowners association or other neighborhood characteristics that affect coverage options, but specific programs vary by location.
Reviewing Insurance Products and Discounts
Whether something significant has changed in your home or community or not, it’s always valuable to review your insurance coverage on a regular basis. For instance, there may be new products or discounts that simply didn’t exist when you originally purchased your policy. Beyond savings considerations alone, ask your agent questions to make sure your coverage still reflects your circumstances and goals.
“Finding savings is always welcome, but the bigger goal of a policy review is making sure your insurance keeps pace with your life and your home,” Anderson said. “A house isn’t static. We improve it, maintain it and protect it in new ways over time. Your insurance should keep up with those changes.”
For more information on homeowner coverage and discount eligibility, visit MercuryInsurance.com.
Questions to Consider During Your Annual Insurance Checkup
An annual insurance review is an opportunity to look for savings and update coverage. Use these questions as a jumping-off point for discussions with your agent:
- What has changed about my home?
- What has changed about my property or community?
- Have my circumstances changed?
- Are discounts available today that weren’t when I purchased my policy?
- Does my coverage still reflect what it would cost to repair or rebuild my home today?
Photos courtesy of Shuttersotck

SOURCE:
📰 Enjoying STM Daily News? Join the conversation!
💬 Leave a comment, share your thoughts, and subscribe to our newsletter for the latest stories, updates, and “News You Can Use This Moment!” delivered to your inbox.
Stay connected with STM Daily News!
Consumer Corner
5 Smart Ways to Prepare Your Home to Weather Storm Season
By readying your home for storm season in advance, you can prevent minor problems from turning into major damage. Consider these five tips to batten down the hatches when the skies are getting dark.
(Feature Impact) Whether your area is prone to thunderstorms, hurricanes, tornadoes or other forms of severe weather, the best time to prepare is before the first raindrop hits. By readying your home for storm season in advance, you can prevent minor problems from turning into major damage.
Consider these five tips to batten down the hatches when the skies are getting dark.
Check Your Roof and Gutters
Your roof has one job – to be a shield against the elements. Don’t wait for a storm to discover you have loose shingles that could fly off in high winds, cracked seals where the roof meets the walls or sagging gutters that aren’t capable of funneling water away from the house. Stay up to date on roof maintenance and clear leaves, twigs and other debris from gutters to prevent clogging.
Trim Trees and Landscaping
Dead trees or weak branches can break and turn into projectiles during storms, potentially causing damage to your house, car or nearby power lines. Next time you have yardwork on the agenda, factor storm preparation into your landscaping plans. Keep trees and bushes trimmed and consider bringing in a professional to assess the health of any trees near your home that could be at risk of toppling.
Strengthen Your Home’s Weak Spots
Windows and doors are some of the most vulnerable places during storms, so pay extra attention to weatherproofing there. Look for any cracks in the glass, check for worn seals or drafty areas and make sure doors close securely and don’t rattle. If you live in an area prone to strong winds or hurricanes, consider upgrading your home with storm shutters for extra peace of mind when debris starts flying.
Turn Your Yard Into a No-Fly Zone
When there’s bad weather in the forecast, you probably aren’t planning to go out and lounge on patio furniture as the skies open up – so pack it up. Secure any items that are too large to bring inside and check around the yard for lightweight items like gardening tools, toys and anything else that could become airborne during strong gusts.
Make a Power Outage Plan
During a storm, nobody wants to fumble around in the dark trying to find batteries for a dead flashlight. Save yourself the trouble by assembling an emergency kit to help your household get by without power if the lines go down. Know where to find flashlights, fresh batteries, power banks to charge your phones, nonperishable food and first-aid supplies or essential medications. If you plan to use a generator, test it and make sure you know how to use it before you need it.
Discover more tips to protect your home at eLivingtoday.com.
Photo courtesy of Unsplash

SOURCE:
🏡 Planning your next home project? Explore expert tips, DIY ideas, product reviews, and the latest home improvement news in Consumer Corner. Share your experiences in the comments and subscribe to the STM Daily News newsletter for practical advice and fresh inspiration delivered straight to your inbox.